The annuity ladder strategy: buying SPIAs in tranches
Instead of buying one large SPIA, split it across multiple purchases at different ages. Potentially higher monthly payouts from later purchases, a partial hedge against inflation, and reduced rate-timing risk.
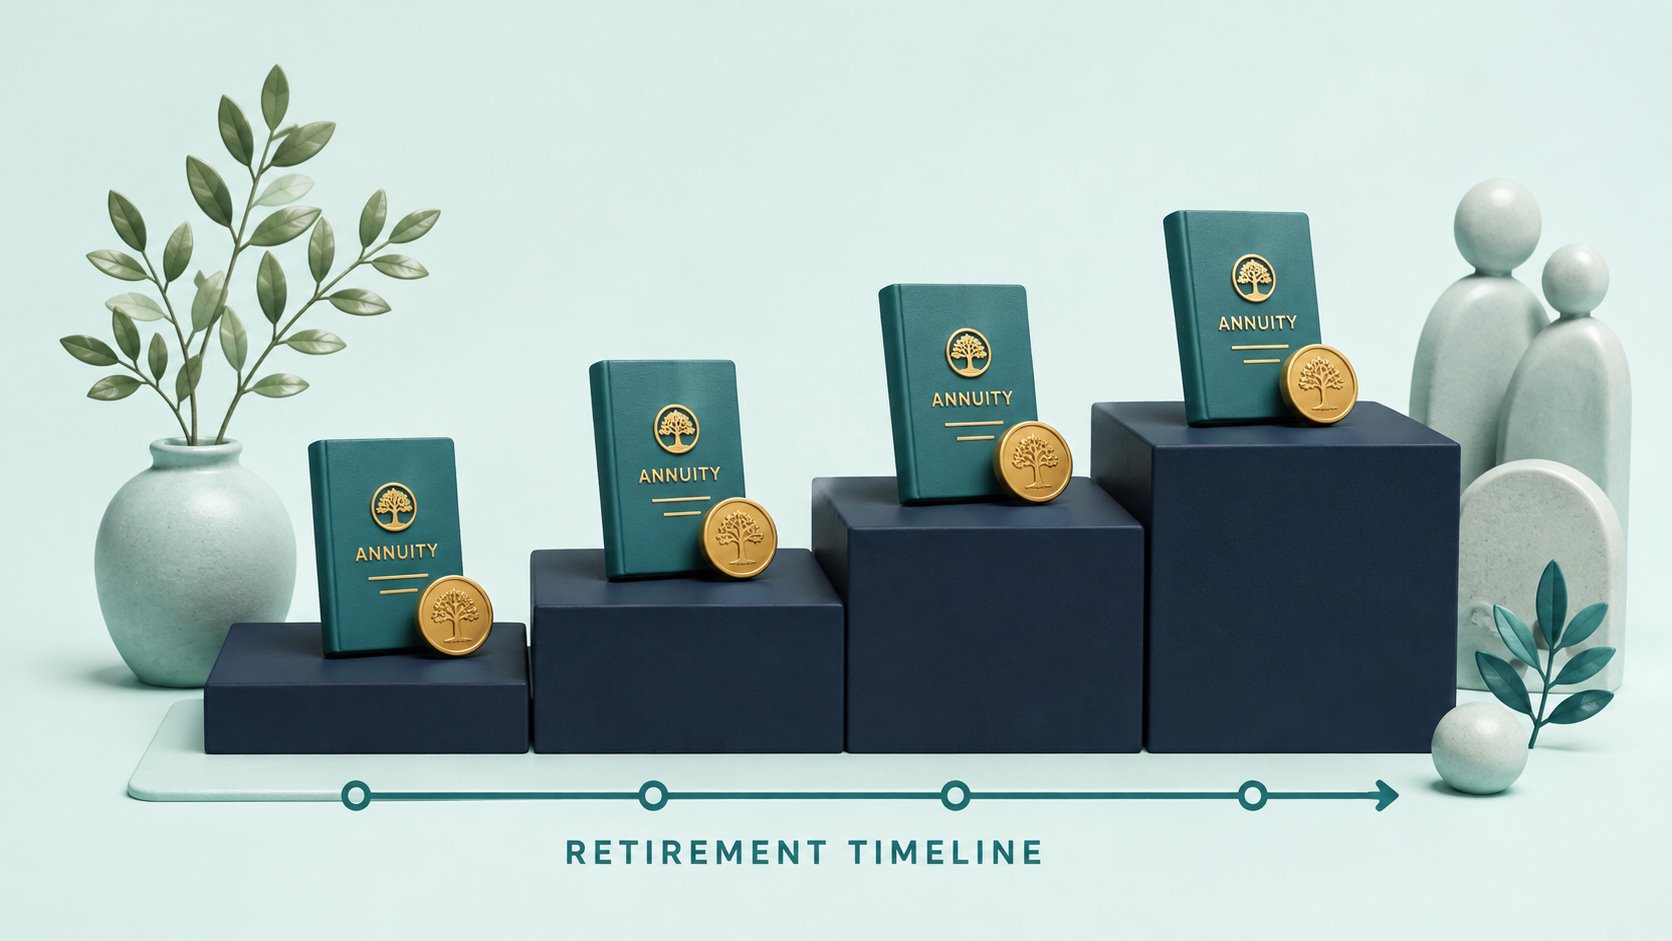
An annuity ladder applies the bond-ladder idea to annuities: instead of committing one lump sum at one rate and one moment, you stagger purchases over time. The payoff is lower interest-rate and timing risk, regular liquidity, and — for income annuities — the higher payouts that come with buying at older ages. This guide covers how the two main ladders work, the real numbers behind them, who they fit, the mistakes to avoid, and how to build one step by step.
What an annuity ladder actually is
A ladder is simply a schedule of purchases. Rather than buying one $300,000 annuity today, you break the money into rungs and buy them across different terms or different years. Each rung does its job independently, and the staggering is what creates the flexibility.
There are two distinct strategies, and it helps to keep them separate because they solve different problems:
- MYGA ladder (rate and liquidity): split money across multi-year guaranteed annuities of different terms (e.g., 3/5/7-year). As each matures you get liquidity and can reinvest at then-current rates — you are never fully locked at one rate.
- Income (SPIA/DIA) ladder: buy income annuities in stages over several years or ages. Later purchases benefit from higher payouts (older age means a shorter expected payout period) and let you dollar-cost-average annuity pricing.
A MYGA is an accumulation product — it grows tax-deferred and returns your principal at maturity. A SPIA (single premium immediate annuity) or DIA (deferred income annuity) converts principal into a guaranteed income stream you typically cannot get back. Laddering works for both, but the goals differ: one preserves and grows safe money, the other manufactures a pension. Any guarantee here rests on the claims-paying ability of the issuing insurer; annuities are not FDIC-insured.
Illustrative, 24% tax bracket, both lines after tax: $6,635 more over 5 years, almost all of it from the rate difference (5.75% vs 4.4%) rather than from deferral. The 4.4% CD leg is an assumed APY, not a quote; the FDIC all-institution average is 1.41%. A MYGA is an insurance contract, not FDIC-insured.
Why ladder instead of one purchase
The case for staggering comes down to four advantages, each of which addresses a real risk in committing everything at once:
- Rate risk: avoids locking your whole balance when rates happen to be low; future rungs can capture higher rates.
- Liquidity: regular maturities provide penalty-free access instead of one long surrender-charge window.
- Payout optimization: staggered income purchases capture rising age-based payouts as you get older.
- Carrier diversification: spreading rungs across insurers reduces single-carrier risk.
None of these requires you to predict rates correctly. That is the point — a ladder is built for the world where you do not know what rates or your health will do next.
A worked MYGA ladder
Say you have $300,000 earmarked for safe, tax-deferred money. Instead of one 5-year MYGA, you split it: $100k into a 3-year, $100k into a 5-year, $100k into a 7-year. To keep the arithmetic clean, assume each contract earns a flat 5% compounded annually (a round illustrative figure, not a quote).
| Rung | Premium | Term | Value at maturity (5% example) | Matures in |
|---|---|---|---|---|
| A | $100,000 | 3 years | ≈ $115,800 | Year 3 |
| B | $100,000 | 5 years | ≈ $127,600 | Year 5 |
| C | $100,000 | 7 years | ≈ $140,700 | Year 7 |
At year 3, rung A matures and roughly $115,800 comes free. You now choose: spend it, renew into a fresh 7-year MYGA at the then-current rate, or annuitize. Two years later rung B does the same, and at year 7 rung C follows. From year 3 onward you almost always have a rung maturing or close to it, so you are never fully locked at one moment's rate — and a rate spike works for your next reinvestment instead of against the whole pile.
A worked income (SPIA) ladder
For lifetime income, staggering works differently: the older you are when you buy a SPIA, the more income each dollar buys, because the insurer expects to pay you for fewer years. That higher rate is not free: money held back for later rungs pays no lifetime income while it waits, only whatever interest it earns in the meantime. In the table below, the $75,000 saved for the age-71 rung goes six years without the roughly $515 a month it would have paid if you had bought at 65. The real gains are spreading out rate and carrier risk and keeping your options open. Suppose you set aside $300,000 and buy a SPIA every two years from age 65.
| Purchase age | Premium | Illustrative monthly income | Annual income added |
|---|---|---|---|
| 65 | $75,000 | ≈ $515 | ≈ $6,180 |
| 67 | $75,000 | ≈ $540 | ≈ $6,480 |
| 69 | $75,000 | ≈ $560 | ≈ $6,720 |
| 71 | $75,000 | ≈ $590 | ≈ $7,080 |
The figures above are round, life-only illustrations for a man of how payouts climb with age, not current quotes. By age 71 your four rungs stack to roughly $2,200 a month in guaranteed income — and each purchase was made at a rate and an age you could not have predicted at 65. You also dollar-cost-averaged annuity pricing and could place each $75k with a different A-rated carrier.
Who it's for vs. who should skip it
A ladder is a decision, so weigh it against your situation rather than treating it as universally smart.
A good fit if you
- Are near or in early retirement and want guaranteed income or principal protection.
- Dislike the idea of timing one large purchase against an unknown rate environment.
- Value periodic liquidity and the option to adjust as your needs change.
- Have enough to spread rungs across more than one carrier.
Probably skip it if you
- Need full, immediate access to the money — annuities are not emergency funds.
- Are confident rates will fall sharply, in which case one long lock would win.
- Have not yet funded tax-advantaged accounts and a cash emergency reserve.
- Have a small balance where multiple contracts add admin without real diversification benefit.
Pros and cons at a glance
| Pros | Cons |
|---|---|
| Hedges interest-rate and timing risk | More contracts and renewal dates to manage |
| Regular liquidity at each maturity | Uncertain rates on future rungs (hurts if rates fall) |
| Income rungs capture rising age-based payouts | Won't beat one long lock if rates only ever drop |
| Easy carrier diversification | Surrender charges still apply if you break a rung early |
Stated honestly: a ladder hedges being wrong about timing; it does not maximize a single best-case outcome. If rates only ever fall, one long lock would have won; if they rise or you value liquidity, the ladder wins.
Mistakes to avoid
Most laddering errors are about the rungs you cannot see yet, not the one you are buying today.
- Ignoring surrender schedules. A ladder gives liquidity at maturity, not before. Cracking a rung early can trigger surrender charges and, before 59½, a 10% tax penalty on gains.
- Chasing the top rate from a weak carrier. A guaranteed rate is only as good as the insurer behind it. Check ratings and complaints; FINRA's investor resources and your state insurance department are good starting points.
- Concentrating everything with one carrier. A guaranteed rate is only as strong as the insurer behind it, so spreading rungs across several highly rated companies limits the damage any single insurer's trouble could do. State guaranty associations are a capped, last-resort backstop — not a reason to buy and not a tool for sizing a purchase.
- Forgetting renewal dates. Maturing MYGAs often roll into a low default renewal rate if you do nothing. Calendar every maturity and decide deliberately.
- Annuitizing money you may need. SPIA and DIA premiums are generally irreversible. Ladder income only with funds you are committing for life.
How to build one: next steps
Translating the strategy into action is a short, ordered checklist:
- Decide the job. Safe growth and liquidity points to a MYGA ladder; guaranteed lifetime income points to a SPIA/DIA ladder.
- Size the rungs. Pick three to five rungs and split the total so no single rung — and no single carrier — exceeds your comfort level.
- Choose terms or ages. Common patterns are 3/5/7-year MYGAs, or income purchases spaced two years apart from your mid-sixties into your seventies.
- Vet each carrier. Confirm financial strength and complaint history before placing any rung; see how to vet carrier safety.
- Track and reinvest. Calendar every maturity, and when a rung comes due, deliberately spend, 1035-exchange, or annuitize it.