An annuity is a contract with an insurance company that converts savings into guaranteed growth or income. The category spans everything from CD-like MYGAs to lifetime-income SPIAs to market-linked indexed products — each with different rates, liquidity, and tax treatment. Use the sections below to find the explainer you need, or jump straight to the rate comparison and our independently scored carrier rankings.
Annuity guides · 59 explainers · Independent
Annuities, explained in plain English.
Every annuity question a serious retiree actually asks — what each product type does, how income and taxes really work, and the trade-offs nobody volunteers — answered independently and checked against primary sources. Start with the foundations, or jump to a topic below.
- 59 plain-English guides
- 6 topics · basics to estate
- Independent carriers can't pay for a ranking
Annuity basics
Start here if annuities are new to you.
 Guide
What is a fixed annuity? A plain-English guide
Fixed annuities pay an insurer-guaranteed rate for a set term and defer tax until you withdraw — not FDIC-insured, with surrender charges for early exits. Here's how they work in 2026.
 Guide
Pros and cons of annuities in 2026
Annuities solve real retirement income problems — but the wrong product can lock you in for decades. Here's the honest tradeoff list.
 Guide
Annuity vs. 401(k): how they actually compare
These two retirement products aren't substitutes — they solve different problems. Here's when each is the better choice.
 Guide
How to buy an annuity: a step-by-step buyer's guide
From defining the goal to comparing carriers to signing the contract — exactly what to do (and not do) when buying an annuity.
 Guide
Qualified vs. non-qualified annuities: the tax difference that changes everything
Where the money came from — IRA or after-tax savings — determines how your annuity is taxed, when you must take distributions, and how heirs are treated. Here's the full breakdown.
 Guide
Income rider vs. annuitization: two ways to turn an annuity into income
Both create lifetime income from an annuity — but one keeps your account balance accessible and one doesn't. Here's how to choose between an income rider and traditional annuitization.
 Guide
How do annuities work? A complete beginner's guide
An annuity is a contract with an insurance company that turns a lump sum into either tax-deferred growth or guaranteed income. Here's exactly how each type works, in plain English.
 Guide
Are annuities a good investment in 2026?
Annuities aren't really 'investments' — they're insurance. That distinction is the key to answering whether they're 'good.' Here's the honest, situation-by-situation answer.
 Guide
Can you lose money in an annuity?
Yes — but only in specific, avoidable ways. Fixed and fixed-indexed annuities don't pass market losses on to you, though leaving early can cost you; variable annuities and RILAs can lose principal. Here's every way you can actually lose money in an annuity, and how to avoid each.
 Guide
What happens to an annuity when you die?
It depends entirely on the annuity type, payout option, and beneficiary setup. Here's exactly what your heirs get (or don't) for every annuity scenario.
 Guide
Pension lump sum vs. annuity: how to decide
When your employer offers a pension buyout — a lump sum or lifetime monthly payments — the choice is irreversible and worth tens of thousands. Here's the framework to decide.
 Guide
Immediate vs. deferred annuity: which timing is right for you?
The core difference is when income starts — now, or later. That single choice changes payouts, taxes, flexibility, and who each product is for. Here's the full comparison.
By product type
MYGA, fixed-indexed, SPIA, variable — explained.
 Guide
MYGA vs. CD: which pays more in 2026?
MYGAs often out-yield same-term CDs and defer the tax, but the gap moves with rates — here is how to compare a specific MYGA's effective yield against a CD's APY. Here's exactly when that gap is worth the trade-offs.
 Guide
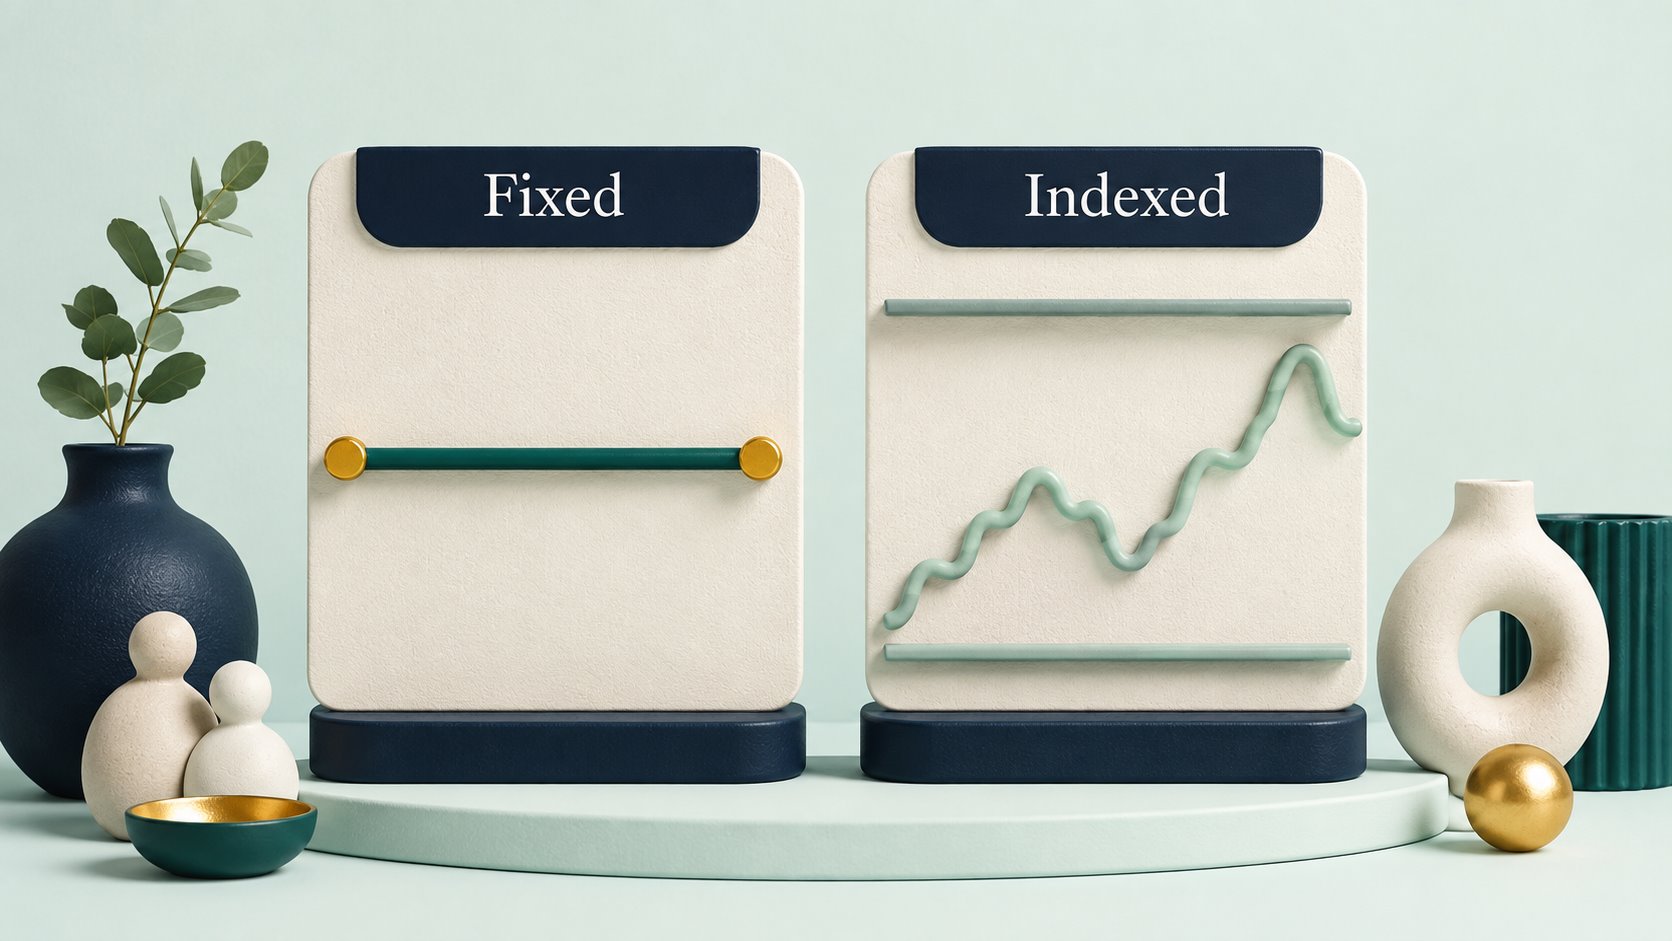
Fixed vs. fixed-indexed annuities: what's the difference?
Fixed annuities guarantee a rate; indexed annuities credit 0% instead of a market loss but cap your gains. Both guarantees depend on the issuing insurer. Here's how to choose.
 Guide
What is a SPIA (Single Premium Immediate Annuity)?
A SPIA converts a lump sum into guaranteed lifetime income, starting within 12 months. Here's how they work and when to use one.
 Guide
What is a variable annuity? Sub-accounts, fees, and living benefits
Variable annuities invest in mutual-fund-like sub-accounts with optional guaranteed-income riders. Here's the trade-off math.
 Guide
Fixed-indexed annuities: cap rates, participation, and spread fees explained
The three levers carriers use to limit your upside on FIAs. Knowing how they interact is the difference between a fair contract and a bad one.
 Guide
Registered Index-Linked Annuities (RILAs): the middle ground
RILAs trade some downside protection for higher upside than fixed-indexed annuities. Where they fit and how they compare.
 Guide
The annuity ladder strategy: buying SPIAs in tranches
Instead of buying one large SPIA, split it across multiple purchases at different ages. Potentially higher monthly payouts from later purchases, a partial hedge against inflation, and reduced rate-timing risk.
Income & payouts
Turning savings into reliable lifetime income.
 Guide
Annuity payout options explained: life, period certain, joint, and more
Life-only, period certain, life with period certain, joint and survivor — how each payout option changes your monthly check.
 Guide
How much does a $100,000 annuity pay per month?
At illustrative October 2026 payout levels, a $100k life-only SPIA for a 65-year-old pays about $670–$700/month for life. Here's the math by age and type.
 Guide
How much does a $500,000 annuity pay per month?
A $500,000 single-life immediate annuity pays a 65-year-old man about $3,490 a month — and roughly $3,275 to $5,380 across ages 60 to 80. Here's the breakdown by age, payout option, and deferral.
 Guide
How much does a $1 million annuity pay per month?
A $1M immediate annuity for a 65-year-old pays $6,690–$6,980/month for life. Here's how that breaks down by age, sex, and joint life options.
 Guide
What is a DIA (Deferred Income Annuity)?
A DIA is a SPIA you buy years before you need the income — for higher payouts when income starts. Also called longevity insurance.
 Guide
Annuity riders: which are worth paying for?
Income riders, death-benefit riders, long-term care riders — which actually add value and which are upsells you can skip.
 Guide
Annuities vs. dividend stocks for retirement income
Both produce income, but one guarantees it and one grows it. Here's the honest comparison between an annuity income stream and a dividend-stock portfolio.
Compare & decide
Head-to-head breakdowns and the math behind them.
 Guide
Annuities vs. bonds: which is right for retirement?
Both provide fixed income, but they're not interchangeable. Here's how MYGAs and SPIAs compare to bonds and bond funds.
 Guide
Annuity vs. CD vs. Treasury: the safe-money trifecta
Three conservative places to park retirement money — backed in three different ways. Here's the apples-to-apples comparison in 2026.
 Guide
Annuity vs. life insurance: when to use each
Annuities pay you while you live. Life insurance pays your beneficiaries when you die. Here's when each (or both) is the right tool.
 Guide
The 4% rule vs. annuities: which produces more retirement income?
The 4% rule is the most famous retirement-income heuristic. Annuities promise more income but less flexibility. Here's the math comparing them — and when each is right.
Taxes & estate
Tax treatment, 1035 exchanges, and inheritance.
 Guide
1035 exchanges: how to swap annuities tax-free
A 1035 exchange lets you move from one annuity to another (or to long-term care insurance) without triggering taxes. The rules and pitfalls.
 Guide
Annuity tax rules: exclusion ratio, LIFO, and the 10% penalty
Two questions set your annuity tax bill: where the money came from (IRA vs. after-tax) and how it comes out (withdrawal vs. annuitization).
 Guide
Inheriting an annuity: rules, taxes, and options
Beneficiary options vary by spouse vs. non-spouse, qualified vs. non-qualified, and the 5-year and 10-year payout rules.
 Guide
Tax-efficient annuity income: structuring withdrawals to minimize taxes
How you draw annuity income — and in what order relative to other accounts — can swing your lifetime tax bill by tens of thousands. Here's the tax-efficient sequencing playbook.
 Guide
Annuities in a trust: rules, tax traps, and when it makes sense
Holding an annuity inside a trust can support estate planning — but it can also blow up the tax deferral. Here's when a trust-owned annuity works and when it backfires.
 Guide
Annuities for a special-needs beneficiary: protecting benefits while providing income
Leaving an annuity to a disabled loved one can disqualify them from SSI and Medicaid — unless it's structured through a special-needs trust. Here's how to do it right.
 Guide
Medicaid-compliant annuities: how they work in long-term-care planning
A specific type of immediate annuity can protect assets while qualifying a spouse for Medicaid long-term-care coverage. Here's how Medicaid-compliant annuities work — and the strict rules.
 Guide
Annuities in divorce: how they're divided, taxed, and transferred
Dividing an annuity in a divorce is more complex than splitting a bank account. Surrender charges, tax traps, and transfer rules can cost both spouses if handled wrong.
 Guide
How annuities interact with Social Security
Annuity income doesn't reduce Social Security benefits, but it can make more of the Social Security you receive taxable — up to 85% of it.
Strategy & planning
Where annuities fit in a full retirement plan.
 Guide
Annuity surrender charges: what you'll really pay to exit early
Surrender schedules typically start at 7–10% and decline over the contract term. Here's how to read them and minimize the hit.
 Guide
The 7 biggest annuity mistakes — and how to avoid them
The seven costliest annuity errors — locking up needed money, chasing teaser rates, picking the wrong payout — with dollar examples and a pre-signing checklist.
 Guide
The annuity free-look period: your no-cost exit window
Most states require — and nearly every contract includes — a 10–30 day window after the annuity arrives to cancel for a refund. Here's what you get back and how to cancel correctly.
 Guide
What's the best age to buy an annuity?
The sweet spot is typically 65–75 — old enough for strong payouts, young enough to lock in for decades. Here's the math by age.
 Guide
All annuity fees, explained: M&E, rider charges, surrender, and more
Mortality & expense charges, sub-account fees, rider costs, surrender charges — every fee that affects your real return.
 Guide
How to retire on $1 million with annuities: a 2026 strategy guide
Whether $1M is enough depends on how you structure it. Here's how to use annuities to convert that $1M into a guaranteed income floor — and what to do with the rest.
 Guide
How to use annuities to bridge to Social Security at 70
Delaying Social Security to age 70 gets you about 24% more than your full-retirement-age benefit (8% a year from 67 to 70) — if you can afford to wait. Annuities can fill the income gap from your retirement date until age 70.
 Guide
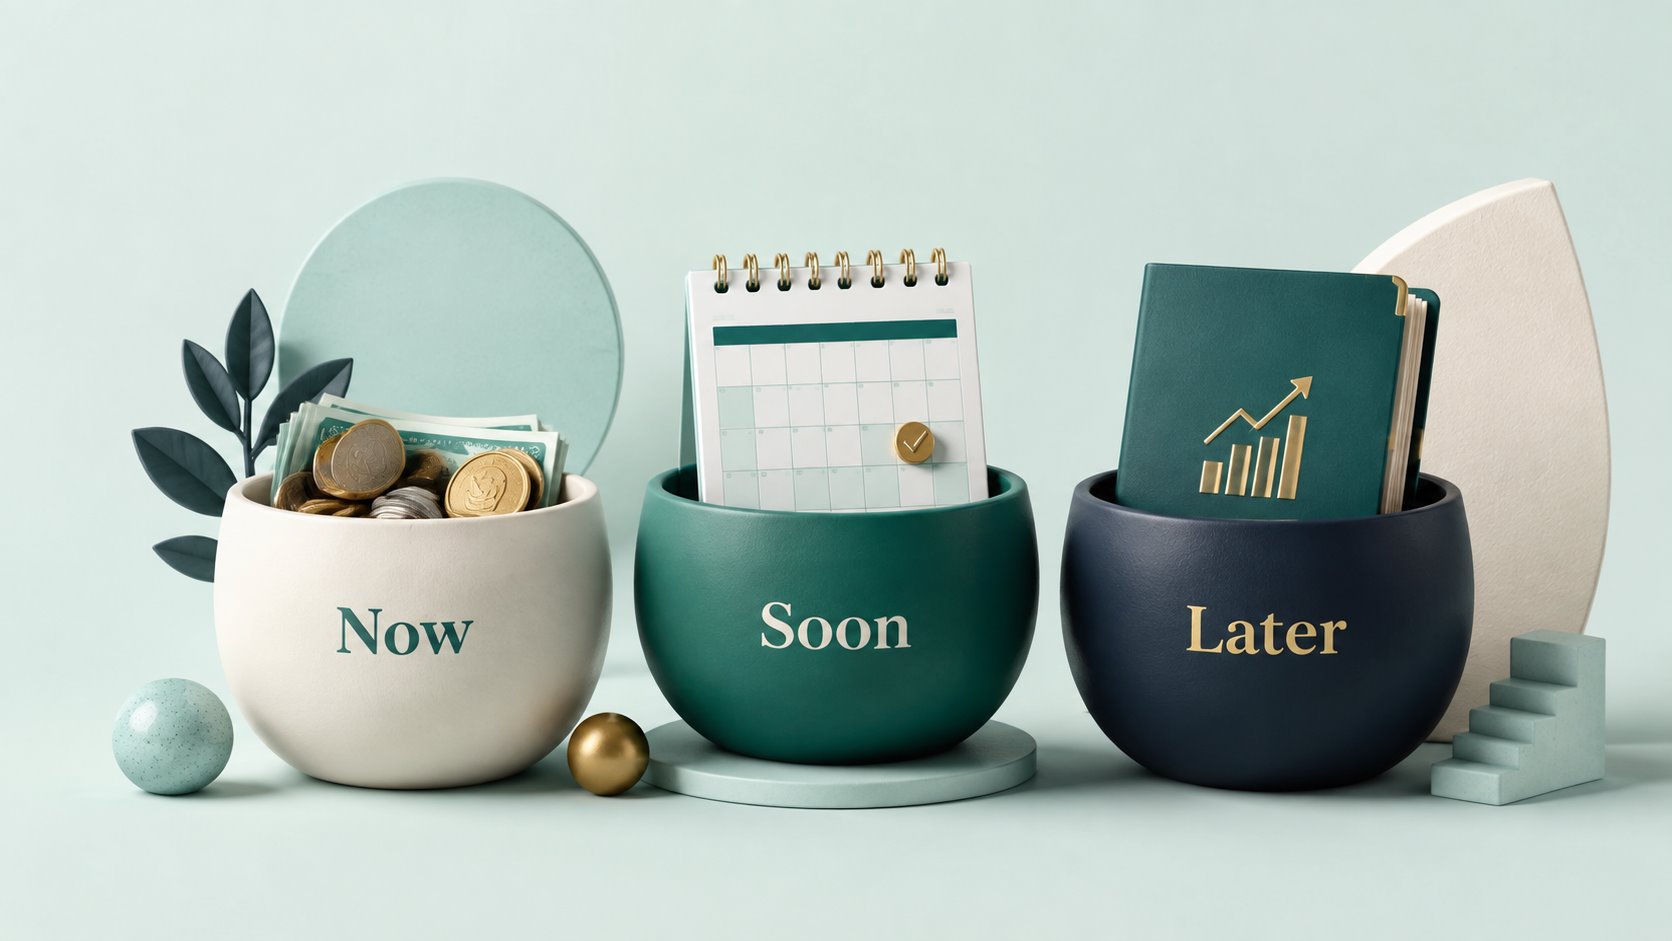
The bucket strategy with annuities: a 3-bucket retirement plan
The bucket strategy organizes retirement assets into time-horizon buckets: cash for now, safe yield for soon, growth for later. Adding an annuity bucket dramatically reduces sequence-of-returns risk.
 Guide
How to retire on $500,000 with annuities
$500k is a tighter retirement budget — which makes structuring it correctly even more important. Here's how annuities can stretch $500k into reliable lifetime income.
 Guide
How to retire on $2 million with annuities
At $2M, you have flexibility most retirees don't. The question shifts from 'will I have enough?' to 'how do I optimize income, taxes, and legacy?' Here's the annuity role at $2M.
 Guide
Retiring at 55 with annuities: the early-retirement playbook
Retiring at 55 means a 35-40 year retirement and a tricky pre-59½ income gap. Here's how annuities fit an early-retirement plan — and the traps to avoid.
 Guide
Retiring at 70 with annuities: maximizing the late-start advantage
Retiring at 70 is the annuity sweet spot — high SPIA payouts, maximum Social Security, and a horizon that makes annuitization mathematically favorable. Here's the playbook.
 Guide
How to vet an annuity carrier's safety: ratings, Comdex, and reserves
An annuity is only as good as the company behind it. Here's exactly how to evaluate a carrier's financial strength using A.M. Best, Comdex, RBC ratios, and state guaranty coverage.
 Guide
Annuity scams and red flags: how to protect yourself
Most annuity 'scams' aren't outright fraud — they're high-pressure sales of unsuitable products. Here are the red flags that signal you should walk away.
 Guide
How annuity commissions work — and why it matters to you
You don't pay annuity commissions out of pocket — but they shape what you're sold and how. Here's exactly how agents get paid and how to use that knowledge.
 Guide
How to roll over a 401(k) without a tax hit
A direct rollover moves your old 401(k) to an IRA with zero tax. Mistakes can trigger income taxes and early-withdrawal penalties. Here is the right way, step by step.
 Guide
7 costly 401(k) rollover mistakes to avoid
Rollovers are simple — until a small misstep triggers taxes, penalties, or years of higher fees. Here are the seven that cost people the most.
More annuity guides
Everything else worth reading.
 Guide
What is a QLAC and how do you use it?
A QLAC lets you defer RMDs on up to $210,000 of IRA money by buying deferred-income annuity coverage. The 2026 rules.
 Guide
How to sell or transfer an annuity
Options include surrendering, 1035 exchanging, or selling future payments to a factoring company. The math on each.
 Guide
Traditional vs. Roth IRA: which should you choose?
The entire decision turns on one question: is your tax rate higher now or in retirement? Here is how to choose, plus the 2026 contribution and income limits.
How these guides are made
Every Track Retirement annuity guide is researched from primary sources and checked before publishing, then updated as rates, tax rules, and products change. Annuity guarantees are subject to the claims-paying ability of the issuing insurer. See our editorial policy.