Fixed vs. fixed-indexed annuities: what's the difference?
Fixed annuities guarantee a rate; indexed annuities credit 0% instead of a market loss but cap your gains. Both guarantees depend on the issuing insurer. Here's how to choose.
A fixed annuity pays a rate you can verify the day you sign. A fixed-indexed annuity (FIA) ties growth to a market index with a 0% floor — the index itself can't push your value down in a down year, but caps and spreads trim what you make in a good one. Neither product's credited value falls when the stock market does, though both can still lose value to surrender charges on an early exit (plus a market value adjustment, on contracts that have one), and an FIA with an optional income rider is charged that rider fee whether or not the index rises. Every guarantee in either contract depends on the claims-paying ability of the issuing insurer — neither is FDIC-insured or government-backed. With that understood, the real decision is simpler than the brochures suggest: is capped, dividend-free upside worth giving up airtight certainty? This guide shows how each one credits interest, what FIAs realistically return, the costs and fine print, who each fits, and a three-step way to decide.
How each one credits interest
The core difference is how the contract turns into a number at the end of the year. A fixed annuity is arithmetic you can do in advance; an FIA is a formula with several moving parts the insurer can adjust.
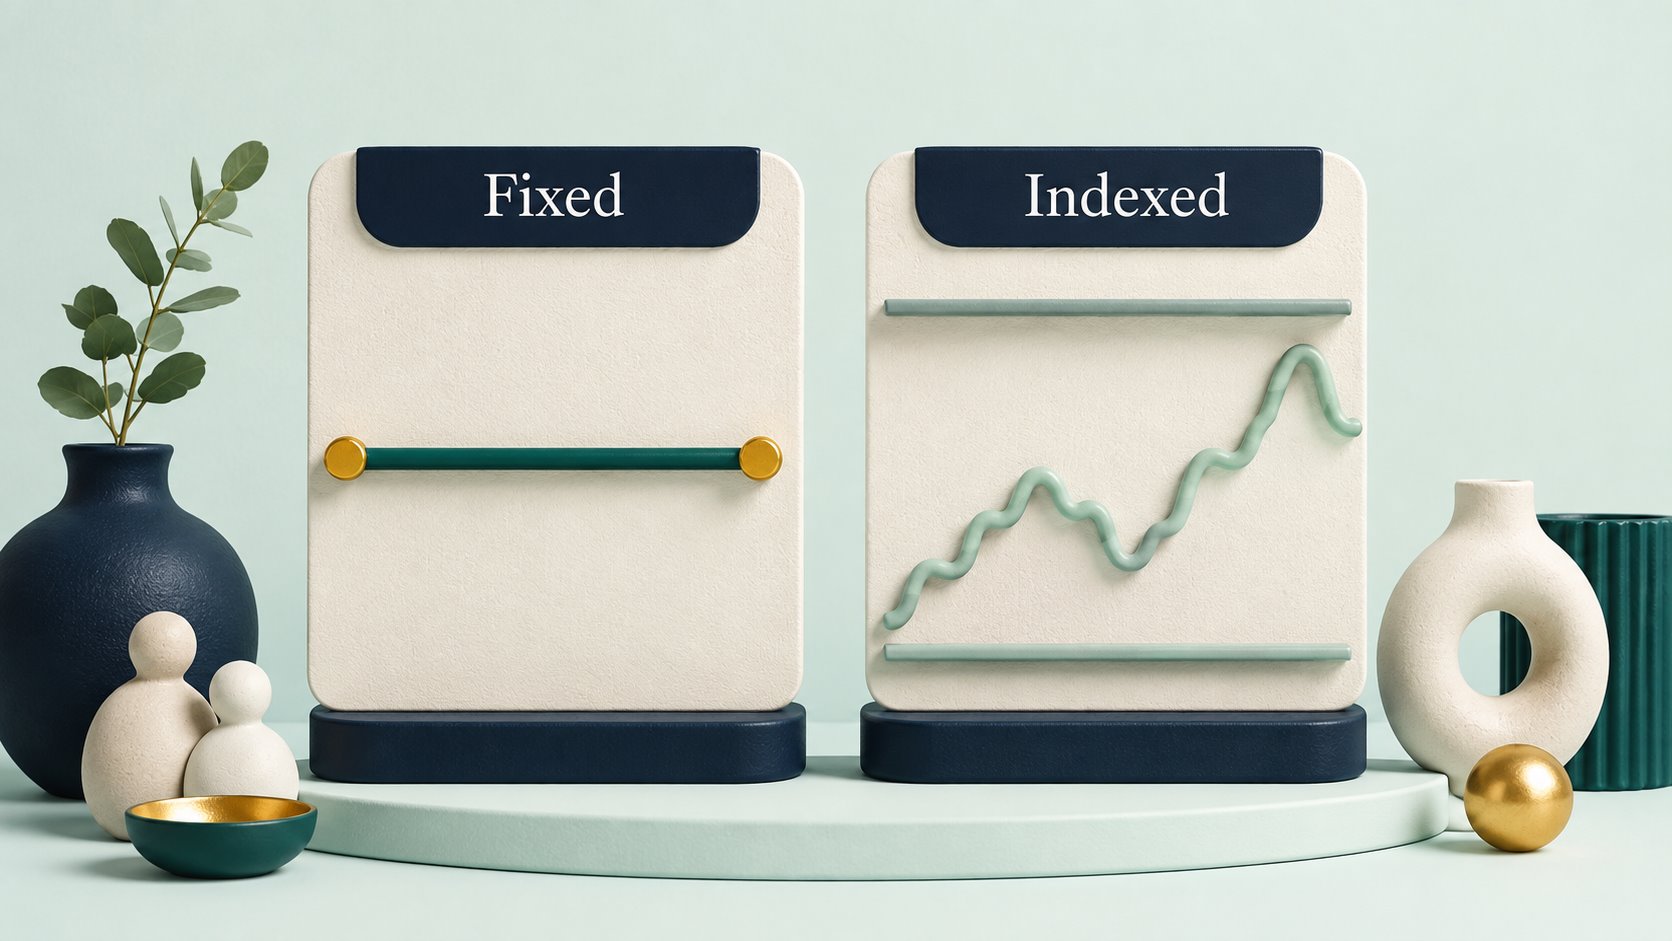
- Fixed (MYGA): a flat guaranteed rate for the term. A multi-year guaranteed annuity (MYGA) locks one rate — say 5.0% — for the full surrender period, so you know the exact ending value the day you sign. Zero ambiguity.
- Fixed-indexed (FIA): 0% in a down year (principal and prior credited gains protected), and a portion of an index's gain in an up year — limited by a cap, a participation rate, and/or a spread that the insurer can reset each term within a contractual minimum.
Three levers shape an FIA's credit. A cap sets the maximum credited (a 6% cap means a 12% index year still credits 6%). A participation rate gives you a percentage of the gain (50% of a 10% gain credits 5%). A spread subtracts a fixed amount first (a 3% spread on a 10% gain credits 7%). Almost every FIA also excludes dividends from the index calculation, which is a meaningful long-run giveback.
The trade, honestly
| Fixed / MYGA | Fixed-indexed | |
|---|---|---|
| Return | Known, guaranteed | 0% to a capped maximum |
| Upside | None beyond the rate | Some, minus dividends & caps |
| Complexity | Low | High (caps/spreads/par, resettable) |
| Best for | Certainty seekers | Conservative money wanting modest upside |
Realistically, an FIA can end up above or below a MYGA's guaranteed rate, depending on its caps and how the index moves, and over a full market cycle it typically trails a dividend-reinvested stock index. It is not "market returns with no risk." You are buying a 0% floor, and you pay for it with capped, dividend-free, resettable upside.
Crediting, with worked numbers
Put $100,000 in each and watch one good index year, using illustrative round numbers. A MYGA at 5.4% credits exactly 5.4% — you end the year at $105,400, known and certain. An FIA's result depends entirely on which lever applies.
| Index rises 10% | FIA crediting method | You earn | Year-end value |
|---|---|---|---|
| Cap = 6% | Lesser of gain or cap | 6.0% | $106,000 |
| Participation = 50% | 50% × 10% | 5.0% | $105,000 |
| Spread = 3% | 10% − 3% | 7.0% | $107,000 |
| MYGA at 5.4% | Flat guaranteed rate | 5.4% | $105,400 |
Now the down year: if the index falls 15%, the FIA credits 0% and your value stays at $100,000 (the floor), while the MYGA still credits its 5.4% and reaches $105,400. The FIA's edge shows up only in strong index years that clear its cap — and the insurer can lower that 6% cap to its contractual minimum next term, which is why the long-run average drifts toward "between a CD and the market."
What FIAs realistically return
Over full cycles, most FIAs deliver more than a CD but well below a dividend-reinvested stock index. Three drags explain the gap: the cap clips your best years, dividends are excluded (and historically dividends are a large slice of total equity return), and caps reset lower when interest rates or insurer budgets fall.
Because these are insurance contracts, the regulator is your state department of insurance, coordinated nationally through the NAIC — not the SEC, which oversees market-based variable annuities. That distinction matters: a market drop does not reduce a fixed or fixed-indexed annuity's credited value, though surrender charges, a market value adjustment (if the contract has one) and optional rider fees can — and every guarantee is only as strong as the insurer.
Costs, surrender charges, and taxes
A plain MYGA usually has no explicit annual fee — the insurer's margin is baked into the rate. FIAs are similar, though optional income riders (guaranteed lifetime withdrawal benefits) often cost roughly 0.5%–1.5% of value per year, charged whether or not the index rises.
Both products carry a surrender period, commonly 5 to 10 years, with a declining penalty — for example 8% in year one fading to 0% — on withdrawals above the free amount. Most contracts let you take out about 10% of the value per year penalty-free.
Growth is tax-deferred: you owe nothing until you withdraw, and gains then come out as ordinary income, not capital gains. Withdrawals before age 59½ generally trigger a 10% IRS penalty on the taxable portion — see IRS Publication 575. Confirm the company's financial-strength and your state guaranty-association coverage limits before you fund either contract; the CFPB has plain-English guidance on annuity basics.
Illustrative projection, not a prediction or a quote: $100,000 at a constant 5% for 20 years, a 24% bracket throughout, no withdrawals, fees or rate changes (a real contract's rate is guaranteed only for its term). Both lines after tax. Deferral changes when you pay tax, not whether; the net advantage here is $14,814, smaller if your bracket rises and larger if it falls.
Who each is for — and who should skip both
This is a decision about your tolerance for the unknown, not about chasing a number.
- Choose a fixed/MYGA if you: want a guaranteed rate you can verify today, value simplicity, dislike caps and resets, or are parking money you'll need at a known date (a CD-like substitute with tax deferral).
- Consider an FIA if you: specifically want some upside with a 0% floor, will genuinely hold through the surrender period, understand the cap/participation/spread mechanics, and have read the guaranteed minimums — not just the current rate.
- Skip both if you: may need liquidity soon, want true market growth (look at low-cost index funds instead), or can't get the crediting terms explained in writing.
Mistakes to avoid
- Pricing the FIA against the stock market. The honest benchmark is a plain MYGA. If the FIA can't beat a guaranteed MYGA rate net of its caps, the floor isn't buying you much.
- Falling for a teaser cap. A high first-year cap that resets to the contractual minimum is a marketing rate, not your expected return.
- Ignoring dividends. "Linked to the index" almost never includes dividends, so the headline index return overstates what you'll credit.
- Overlooking surrender liquidity. Locking money you may need inside a 7-year surrender schedule can cost more than any upside you gain.
- Skipping the insurer's strength. The guarantee depends on the company; check ratings and your state guaranty limits first.
How to decide
Price the FIA against a plain MYGA, not against equities. For pure certainty and simplicity, the MYGA wins. An FIA earns its place only if you specifically want some upside with a floor, understand the caps, and will hold it through the surrender period. See how caps, participation and spreads work.
A clean three-step check: (1) get the MYGA's guaranteed rate and the FIA's guaranteed minimum caps in writing; (2) run both through the calculator above against your time horizon; (3) confirm the surrender schedule, free-withdrawal allowance, and the insurer's financial strength before signing anything.