Annuity vs. life insurance: when to use each
Annuities pay you while you live. Life insurance pays your beneficiaries when you die. Here's when each (or both) is the right tool.
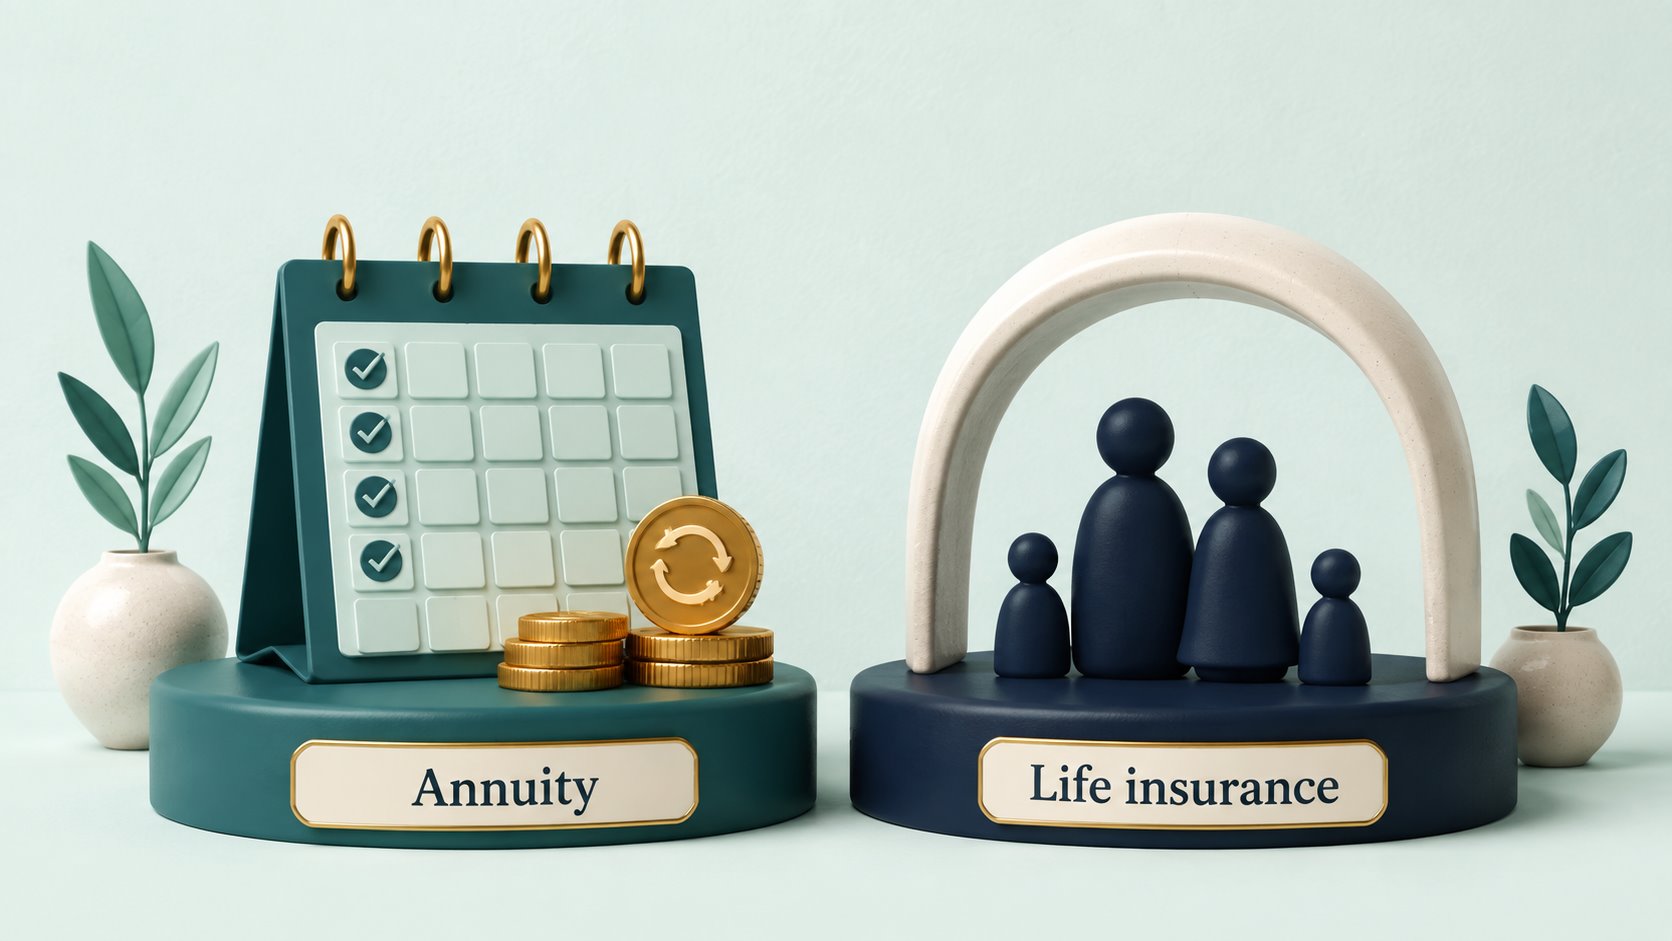
Here's the bottom line: life insurance protects the people who depend on you if you die too soon, and an annuity protects you from running out of money if you live too long. They hedge opposite risks, so the real question isn't "which is better"—it's "which risk am I facing right now." This guide walks through how each works, what they cost, who needs which, the scenarios where you want both, and the mistakes that cost people the most.
Opposite jobs, not competitors
Annuities and life insurance are often sold by the same agents and confused constantly—but they solve opposite problems. Getting which one you need right is the whole decision.
- Life insurance protects against dying too soon. It pays your dependents a lump sum if you die while they still rely on your income.
- An annuity protects against living too long. It converts a pile of savings into income you can't outlive in retirement.
One insures your death; the other insures your longevity. They tend to matter at different life stages: most people need term life while they're working and raising a family, and may want some annuitized income decades later in retirement. Thinking of them as competitors is the first mistake—they're tools for two different jobs.
Illustrative projection, not a prediction or a quote: $100,000 at a constant 5% for 20 years, a 24% bracket throughout, no withdrawals, fees or rate changes (a real contract's rate is guaranteed only for its term). Both lines after tax. Deferral changes when you pay tax, not whether; the net advantage here is $14,814, smaller if your bracket rises and larger if it falls.
Quick contrast
| Life insurance (term) | Annuity (income) | |
|---|---|---|
| Risk hedged | Premature death | Outliving savings |
| Who benefits | Your beneficiaries | You, while alive |
| Best life stage | Working / raising a family | Retirement |
| Typical buyer age | 25–55 | 60–80 |
| Underwriting | Full medical + financial | Light (age + premium) |
| Payout taxation | Income-tax-free death benefit | Ordinary income on the gain portion (all of it if bought with pre-tax IRA/401(k) money) |
| Taxes on what heirs receive | Generally income-tax-free | Ordinary income on any gain; no step-up in basis |
How each one actually works
Term life insurance is the simplest version: you pay a level premium for a set period—say 20 or 30 years—and if you die during that term, your beneficiaries receive the death benefit tax-free. If you outlive the term, coverage ends and you've paid only for protection, not savings. It's cheap precisely because most policies never pay a claim.
Permanent life insurance (whole or universal life) is built to last your whole life as long as it stays funded—a universal life policy can lapse if premiums or cash value run short—and builds a cash value you can borrow against, but it costs many times more than term for the same death benefit because you're funding an investment account wrapped in insurance.
An income annuity works in reverse. You hand an insurer a lump sum—or pay over time—and in exchange it sends you a guaranteed check, either for a set number of years or for the rest of your life. A single-premium immediate annuity (SPIA) starts paying right away; a deferred income annuity starts years later, often acting as "longevity insurance" that kicks in at 80 or 85. The older you are when payments begin, the larger each check, because the insurer expects to pay you for fewer years. For a neutral primer on both product families, see the SEC's investor portal at investor.gov and FINRA.
The real numbers: a worked example
Numbers make the contrast concrete. These figures are round and illustrative—your actual quotes will vary by age, health, rates, and insurer—but the relationships hold.
Life insurance side. Say you're a healthy 35-year-old buying a $500,000, 20-year term policy. A typical premium might run about $30/month, or roughly $360/year. Over the full 20 years you'd pay around $7,200 total—and your family receives $500,000 tax-free if you die during the term. Compare that to a permanent policy for the same $500,000 death benefit, which could easily cost $400+/month. The price gap is the cost of the cash-value feature, not better protection.
Annuity side. Now jump forward 30 years. At 65, you take $200,000 and buy a single-life SPIA paying a man, say, $1,396/month ($16,752/year) for life. If you live 25 years to age 90, you collect about $419,000—a $219,000 gain over your principal. The catch: with a pure life-only payout, if you die at 70 the insurer keeps the remaining balance. Add a 10-year period-certain guarantee and the payment might drop to about $1,312/month—roughly $84/month, or 6%, less—in exchange for a guarantee that payments last at least 10 years in total: if you die after four years, your beneficiary gets the remaining six. That trade-off, more security for a smaller check, is the central annuity dial.
Where the confusion is sold
Permanent life insurance with cash value is sometimes pitched as an "investment" or "retirement" product to compete with annuities. For most people's pure needs, term life (cheap death-benefit protection) plus, later, a simple income annuity beats a complex bundled product on both cost and clarity. Your state insurance department and the SEC publish neutral primers worth reading before you sign.
Who needs which—and who should skip each
The decision usually comes down to who depends on your money and when.
You probably need life insurance if…
- You have children, a spouse, or anyone who'd struggle financially without your income.
- You carry a mortgage or co-signed debt that wouldn't vanish at your death.
- You're the higher earner in a two-income household, or a stay-at-home parent whose unpaid labor would have to be replaced.
You can probably skip or scale back life insurance if…
- You're single with no dependents and no co-signed debt.
- You're financially independent and your assets already cover any survivors.
- Your kids are grown and your mortgage is paid—your need may have simply ended.
You might want an annuity if…
- You fear outliving your savings more than you fear leaving less to heirs.
- You have little or no guaranteed income beyond Social Security and want a private "paycheck" floor.
- You'd sleep better knowing a baseline of essential expenses is covered no matter how markets perform or how long you live.
An annuity is a poor fit if…
- Your guaranteed income (pension plus Social Security) already covers your needs—check your estimate at ssa.gov.
- Leaving a large inheritance is your top priority.
- You'd need the lump sum back on short notice; surrender charges can lock it up for years.
Pros and cons at a glance
| Pros | Cons | |
|---|---|---|
| Term life insurance | Cheap; large tax-free benefit; simple to compare | Expires; no cash value; premiums rise sharply if you renew older |
| Permanent life insurance | Lifelong coverage; cash value; estate-planning uses | Expensive; high fees; complex; easy to overpay for what you need |
| Income annuity (SPIA) | Guaranteed lifetime income; longevity protection; simple payout | Illiquid; basic version leaves nothing to heirs; locks in current rates |
When you actually need both
Plenty of households use both—just not for the same reason. A retiree in their late 60s with a surviving-spouse income gap is a classic case: a SPIA to lock in lifetime income, plus a small term-life policy to bridge the spouse's first few years if the annuity is single-life.
That pairing is not automatically cheaper than a joint-life SPIA with a 100% survivor benefit. Term coverage bought in your late 60s needs medical underwriting, can be expensive, and ends when the term does, while a joint-and-survivor SPIA keeps paying your spouse for life. In the example above, a 100% joint version might pay about $1,089/month instead of $1,396 (about $3,700 a year less). Compare that with real term quotes before you give up the survivor benefit. The general framework: use life insurance to protect against dying early and an annuity to protect against living long, and let each do only its own job.
Mistakes to avoid
- Buying permanent life "for retirement." It's an inefficient way to invest and an inefficient way to insure. Separate the two functions.
- Annuitizing everything. Once you hand over the lump sum, it's gone. Annuitize only the slice needed to cover essential expenses, and keep the rest liquid.
- Ignoring inflation. A fixed $1,396/month check buys far less in 20 years. Consider a cost-of-living rider or keep growth investments alongside the annuity.
- Letting term coverage lapse too early. If you outlive your policy but still have dependents, you may be uninsurable or facing far higher premiums.
- Skipping the fine print. Surrender charges, riders, and fees quietly erode value. Read the schedule before you sign.
How to decide and what to do next
- Name the risk. Are people relying on your income today (death risk), or are you worried about your own savings lasting (longevity risk)? That answer points to the product.
- Size the gap. For life insurance, estimate what your survivors would need to replace your income and clear debts. For an annuity, project your guaranteed income against essential expenses—the retirement income calculator above helps.
- Get apples-to-apples quotes. Compare term policies of the same death benefit and length; compare annuities of the same payout structure. Don't let one product's bells and whistles cloud the comparison.
- Check the issuer and the costs. Verify financial-strength ratings, fees, surrender terms, and commissions in writing before committing.