Income rider vs. annuitization: two ways to turn an annuity into income
Both create lifetime income from an annuity — but one keeps your account balance accessible and one doesn't. Here's how to choose between an income rider and traditional annuitization.
To turn an annuity into lifetime income you have two paths: annuitize the contract, or use a guaranteed lifetime withdrawal benefit (GLWB) rider. They reach the same destination — a check that arrives for as long as you live — but they differ sharply on liquidity, cost, and what's left for heirs. This guide breaks down how each works, the real numbers behind a typical decision, who should pick which, and the traps that quietly cost retirees thousands.
The fundamental difference
Both options solve the same problem: converting a pile of savings into income you can't outlive. The mechanics are opposite, though, and that gap drives every tradeoff below.
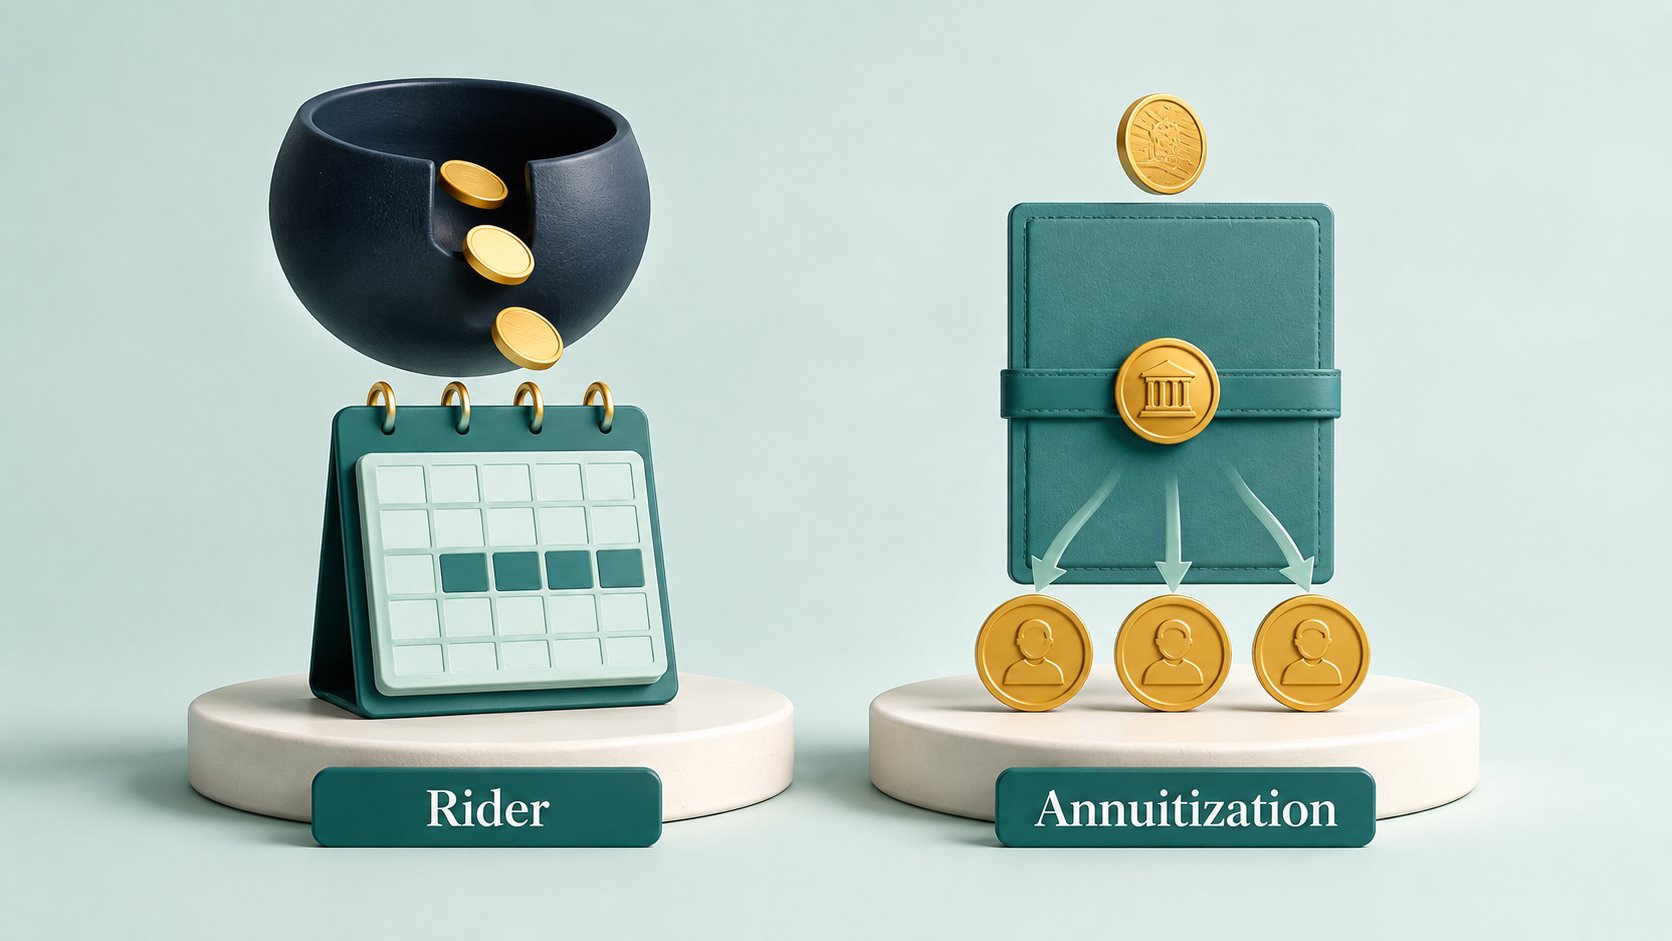
- Annuitization: you irrevocably convert the balance into a payment stream. It delivers the highest income per dollar, but you generally give up access to the lump sum and — without an added option — leave nothing to heirs.
- GLWB rider: you keep the account; the rider guarantees you can withdraw a set percentage for life even if the account balance hits zero. You retain liquidity and any remaining account value for heirs, but you pay an annual rider fee and usually collect lower lifetime income.
Put simply, annuitization buys the biggest check by surrendering control. A GLWB keeps control and a possible inheritance by accepting a smaller check and an ongoing fee.
How annuitization works
When you annuitize, the insurer pools your money with thousands of other annuitants and pays income funded by three things: your principal, interest, and mortality credits — the balances of people who die earlier than expected, redistributed to those who live longer. That mortality pool is why annuitization produces more guaranteed income per dollar than any do-it-yourself strategy. Any guarantee here rests on the claims-paying ability of the issuing insurer; annuities are not FDIC-insured.
The cleanest version is a single-premium immediate annuity (SPIA): you hand over a lump sum and payments begin within a year, with no ongoing fees because the cost is baked into the payout rate. You choose the structure up front — life only (largest check, stops at death), life with cash refund (smaller check, guarantees heirs get back any premium not yet paid out to you), life with period certain (smaller check, guarantees payments for a set number of years, which may add up to less than your premium), or joint life (covers two people). A payout rate is not an interest rate: most of each early check is your own principal coming back to you, so the percentage is not comparable to a bond or CD yield.
The catch is permanence. Once the contract is annuitized, the decision is generally irrevocable: no lump-sum access, no changing your mind if your health declines or an emergency hits.
Illustrative single-life payout by starting age — representative levels for A.M. Best A− and above carriers, not a survey or quote. Payout levels as of October 2026. A female buyer's check runs about 4.2% lower at 65 and 7.1% lower at 80, reflecting longer life expectancy. Actual quotes vary by carrier, state, sex and payout option.
How an income rider works
A GLWB is an optional feature attached to a deferred annuity — usually a fixed indexed annuity (FIA) or variable annuity (VA). You keep your account and its cash value; the rider layers a separate promise on top: you may withdraw a guaranteed percentage each year for life, even if the account itself runs dry.
That guaranteed percentage is applied to a benefit base (also called the income base), a bookkeeping number that often grows by a contractual "roll-up" rate during the years before you start income. Critically, the benefit base is not spendable money — it exists only to size your guaranteed withdrawal.
The rider charges an annual fee, commonly in the 0.95%–1.50% range, deducted from your cash value every year whether the markets cooperate or not. In exchange, you keep liquidity (subject to the contract's surrender schedule) and your heirs receive whatever cash value remains.
Side by side
Here's the whole decision compressed into one view.
| Annuitize (SPIA-style) | GLWB rider (on FIA/VA) | |
|---|---|---|
| Income per dollar | Highest — pure mortality pool | Lower — rider fee plus accumulation math |
| Liquidity | None (irrevocable) | Cash value stays available (with surrender schedule) |
| Legacy | Only with refund/period-certain option | Remaining cash value to heirs |
| Ongoing fee | None (built into payout rate) | ~0.95%–1.50% per year |
| Best for | Maximizing the guaranteed check | Flexibility plus a guaranteed income floor |
Worked example: $250,000 at age 65
Picture a 65-year-old man comparing the two approaches on $250,000. These are round, illustrative figures — your real quotes depend on rates, gender, and contract terms — but they show the shape of the tradeoff.
- Annuitize as a SPIA: a life-only payout of roughly $1,745/month, or about $20,940 per year, starting at 65. The income is irrevocable, and under a life-only structure, $0 goes to heirs if you die in year one.
- Income rider on an FIA (assume a 5% compound roll-up and a 5% payout factor at the start age): after deferring five years, the benefit base grows from $250,000 to about $319,000, and 5% of that is roughly $15,950 per year, or about $1,330/month, starting at 70. Your cash value (which could be above or below $250,000 after five years of credits and fees) stays available, subject to any surrender charges, and passes to heirs.
Step through the gap, and compare checks that start at the same age. The SPIA starts five years sooner, so it pays about $104,700 before the rider's first check at 70. And if you waited to buy the SPIA at 70, the same $250,000 would pay about $1,920 a month, or roughly $23,070 per year. That is about $7,120 more per year than the rider's $15,950, roughly 45% more income for life. That difference is the literal price of liquidity and legacy. Over 20 years from age 70, it adds up to more than $140,000. In return, the rider holder keeps access to a cash balance, but it shrinks every year as the withdrawals and the rider fee come out of it. It may run out in your late 80s or 90s; after that, the insurer keeps paying the $15,950 for life.
Who should annuitize vs. who should use a rider
This is fundamentally a values question, not a math question. Decide by how much you weigh the largest possible check against control and inheritance.
Annuitization is the better fit if you:
- Want the maximum guaranteed income per dollar and will spend it, not hoard it.
- Have no heirs to provide for, or have legacy covered by other assets.
- Are in good health with longevity in your family, so mortality credits work in your favor.
- Value simplicity and a zero-fee structure over flexibility.
A GLWB rider is the better fit if you:
- Want a guaranteed income floor but can't stomach giving up access to the principal.
- Care about leaving residual value to heirs.
- Can defer income several years to let the roll-up do its work.
- Want some upside participation (on an FIA/VA) alongside the guarantee.
Pros and cons at a glance
No option is strictly better; each trades something real.
- Annuitization pros: highest income, no fees, dead-simple, immune to market and sequence risk.
- Annuitization cons: irrevocable, illiquid, inflation erodes a fixed payment, nothing to heirs without a refund option.
- GLWB pros: keep liquidity and your account, residual to heirs, guaranteed income floor even if the account hits zero, potential index upside.
- GLWB cons: lower income, annual fee drags on growth, complex contracts, the alluring benefit base is not cash you can take.
Mistakes to avoid
The errors here are predictable and costly, and most stem from misreading how these products work.
- Treating the benefit base as cash. A 7% roll-up on the income base is not 7% account growth. You cannot withdraw or inherit the base — only the cash value.
- Ignoring the fee drag. A 1.25% rider fee, usually calculated on the (often larger) benefit base and taken out of your cash value every year, compounds against you; over a long deferral it meaningfully reduces what's left for heirs.
- Buying a rider then taking income immediately. You pay for a deferral benefit you never use. If you need income now, price a SPIA first.
- Skipping the insurer's strength. These guarantees rest on the insurer's solvency, not the FDIC. State guaranty associations offer limited backup — verify ratings and coverage.
- Not shopping quotes. SPIA payout rates and rider terms vary widely between carriers for the same premium and age.
How to decide and what to do next
Work through this in order before you sign anything.
- Define the job for this money. Is it maximum spendable income, a guaranteed floor with flexibility, or an inheritance? Your answer points to one path.
- Get real quotes, not illustrations of the benefit base. Ask each carrier for the actual guaranteed monthly check, the fee, and the surrender schedule in writing.
- Compare apples to apples. Line up the SPIA monthly payment against the rider's guaranteed lifetime withdrawal at the same start age, after fees.
- Vet the insurer. Check financial strength ratings from A.M. Best, S&P, Moody's or Fitch, and your state guaranty association's coverage limits (find your state's association at nolhga.com). For how variable-annuity riders and fees are regulated and disclosed, review investor guidance from FINRA and the SEC.
- Model the taxes. Confirm whether the money is qualified or non-qualified, since that changes how each payment is taxed under IRS Publication 575.