Qualified vs. non-qualified annuities: the tax difference that changes everything
Where the money came from — IRA or after-tax savings — determines how your annuity is taxed, when you must take distributions, and how heirs are treated. Here's the full breakdown.
"Qualified" versus "non-qualified" is not a product difference — it describes the money you used to buy the annuity. That single distinction drives the taxes you owe on the way out, whether contribution limits apply, whether you're forced to take withdrawals, and what your heirs inherit. Here's the full breakdown, with the numbers that show why it matters.
The core difference
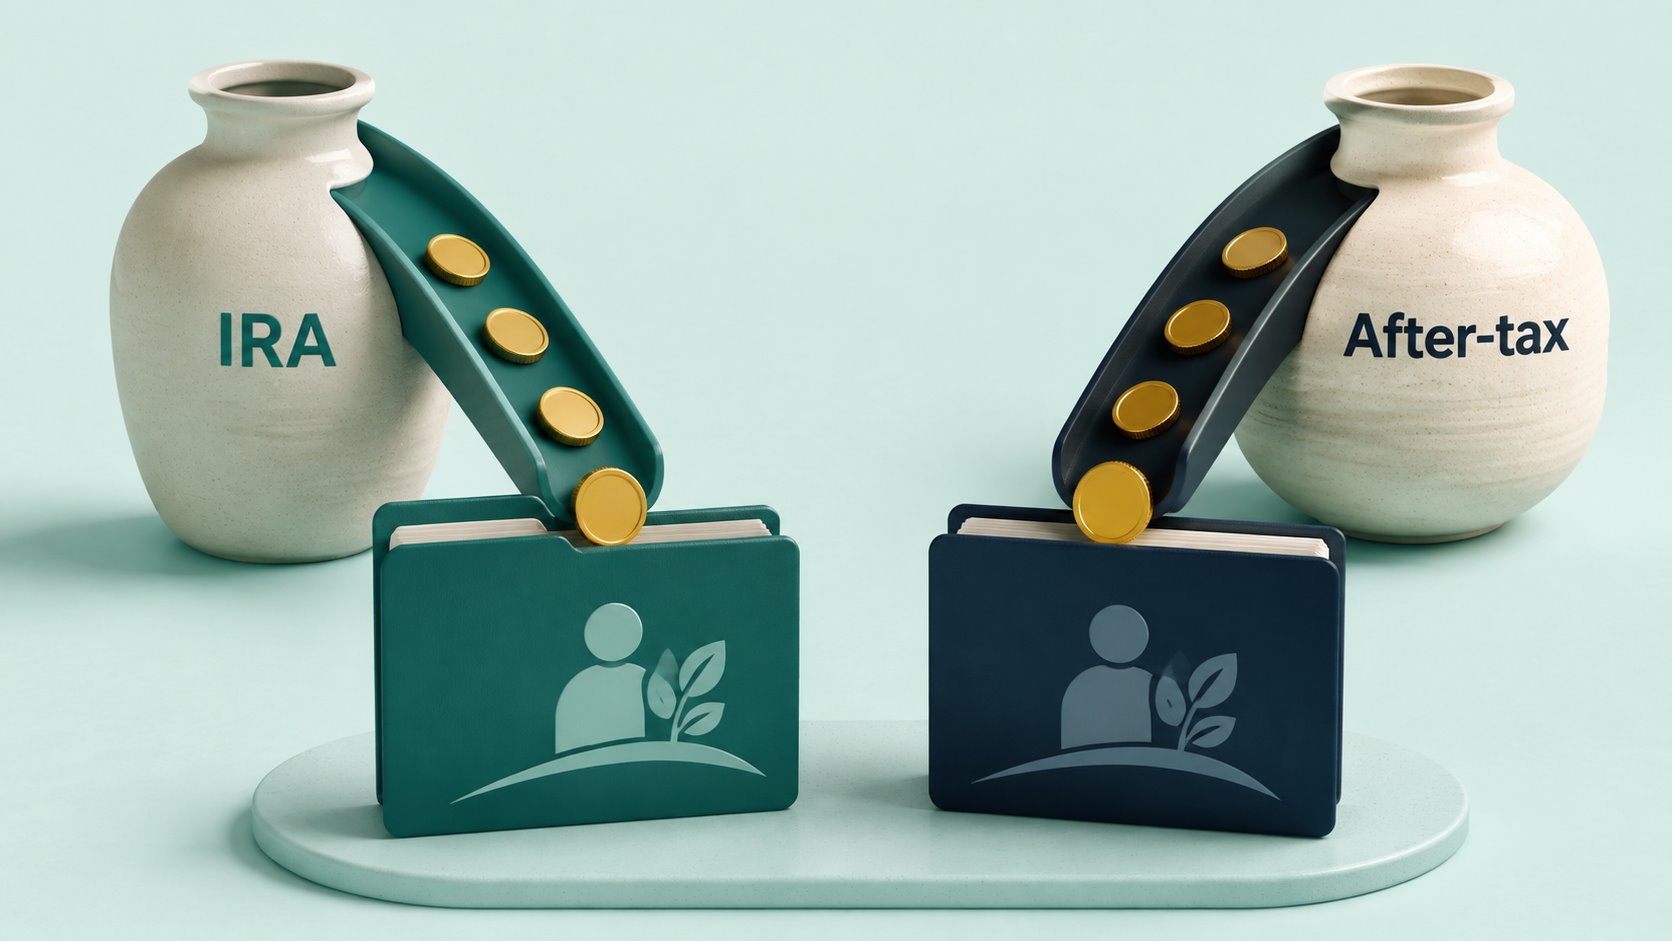
A qualified annuity is funded with pre-tax dollars — money inside an IRA, 401(k), or similar plan that has never been taxed. A non-qualified annuity is funded with after-tax dollars from your bank or brokerage savings. Same insurance contract; completely different tax treatment.
| Qualified | Non-qualified | |
|---|---|---|
| Funded with | Pre-tax (IRA/401k) | After-tax savings |
| Tax on withdrawal | Entire amount taxable (traditional pre-tax; Roth and after-tax basis differ) | Only the gain taxable (LIFO) |
| Contribution limit | IRA/401k limits apply | No IRS contribution limit |
| RMDs | Yes (follows account rules) | No RMDs |
| Heir tax treatment | Ordinary income; 10-yr rule for most non-spouse heirs | Ordinary income on gain only; no step-up; 5-year or life-expectancy payout for non-spouse |
Illustrative projection, not a prediction or a quote: $100,000 at a constant 5% for 20 years, a 24% bracket throughout, no withdrawals, fees or rate changes (a real contract's rate is guaranteed only for its term). Both lines after tax. Deferral changes when you pay tax, not whether; the net advantage here is $14,814, smaller if your bracket rises and larger if it falls.
How each one is taxed
With a qualified annuity, you funded it with money that was never taxed, so the IRS taxes everything on the way out — both your original contributions and all growth — as ordinary income. That describes traditional, all-pre-tax accounts; a Roth IRA annuity or after-tax contributions follow different rules (qualified Roth distributions are tax-free, and after-tax basis is returned untaxed). Required minimum distributions apply once you reach RMD age, just as they would for any IRA or 401(k).
With a non-qualified annuity, you already paid tax on the principal, so only the gain is taxable. During the accumulation phase, withdrawals are LIFO — last in, first out — meaning gains come out first and are fully taxed before you reach your tax-free basis. There are no RMDs, so the contract can keep compounding untouched for as long as you like.
If you convert a non-qualified annuity into a lifetime income stream (annuitize), the tax math changes: an exclusion ratio splits every payment into a tax-free return of your basis and a taxable portion of gain, until your basis is fully recovered. The IRS spells this out in Publication 575.
A worked tax example
Say you put $100,000 of after-tax savings (non-qualified) into a MYGA and it grows to $128,000. You withdraw $28,000. Under LIFO, that entire $28,000 is gain and is taxed as ordinary income; your $100,000 basis is still intact and will come back tax-free. At a 24% bracket, the tax is about $6,720 — and nothing is owed on the principal.
Now put $100,000 of IRA money (qualified) into the same annuity, let it grow to $128,000, and withdraw $28,000. Every dollar is ordinary income because none of it was ever taxed (a traditional, all-pre-tax IRA — Roth and after-tax money differ): at 24% that's $6,720 on this withdrawal — but eventually the entire $128,000 will be taxed as you draw it down, and RMDs force you to start. Same product, same growth, very different lifetime tax bill — driven entirely by the money you used.
The mistake to avoid
Putting an annuity inside a qualified account (IRA/401k) purely for "tax deferral" is redundant — the account is already tax-deferred. You can't defer taxes that are already deferred, so you'd be paying annuity fees for a benefit you already own.
A qualified annuity inside an IRA only earns its keep when you want a guarantee itself — a contractual lifetime paycheck, a MYGA's fixed rate weighed against IRA CDs and Treasuries, or a QLAC (qualified longevity annuity contract) that lets you defer RMDs on a slice of your IRA to a later age. Both FINRA and the SEC flag the "annuity in an IRA for tax reasons" sales pitch as a red flag worth questioning.
The IRA-annuity mistake, quantified
Here's the cost of the redundant-deferral trap in dollars. Suppose an annuity wrapper adds just 1% in annual fees on a $200,000 IRA balance. That's roughly $2,000 per year — and because the IRA was already tax-deferred, that $2,000 is buying you nothing on the tax side. Over 10 years, before compounding, that's about $20,000 spent for a benefit you already had.
Inside an IRA, an annuity is only worth that cost when the income guarantee or longevity protection is what you actually want. For pure tax-deferred growth, the IRA alone already does the job. See our deeper dive on annuity tax rules.
Where each one fits
The right choice follows the money. Use this matrix to match the funding source to the job the annuity should — and shouldn't — do.
| Money source | Use an annuity for… | Avoid it for… |
|---|---|---|
| After-tax (non-qualified) | Tax-deferred fixed growth once 401(k)/IRA are maxed; uncapped contributions | Money you may need before the surrender period ends |
| IRA/401(k) (qualified) | Guaranteed lifetime income, or a QLAC to defer RMDs | "Extra tax deferral" — it's redundant inside an IRA |
- Non-qualified annuity is for you if: you've already maxed your 401(k) and IRA, you're in a higher bracket, and you want more uncapped, tax-deferred growth with no RMDs.
- Qualified annuity is for you if: you want to convert retirement money into a guaranteed lifetime paycheck, or use a QLAC to push RMDs later — not to chase deferral you already have.
- Skip the annuity if: you might need the cash before the surrender period ends, or you're being sold "tax savings" inside an account that's already tax-advantaged.
Pros and cons at a glance
Both types share the core annuity tradeoffs — tax-deferred growth and optional lifetime income in exchange for fees and limited liquidity. The differences come down to taxes, access, and inheritance. Any guarantee here rests on the claims-paying ability of the issuing insurer; annuities are not FDIC-insured.
- Non-qualified pros: no contribution limit, no RMDs, only gains taxed, basis returns tax-free.
- Non-qualified cons: no upfront deduction (you funded it with taxed money), LIFO means gains are taxed first, no step-up in basis for heirs.
- Qualified pros: funded with pre-tax dollars, useful for guaranteed income and QLAC-based RMD deferral.
- Qualified cons (traditional pre-tax accounts): every dollar taxed as ordinary income, RMDs are mandatory, and the deferral benefit is redundant inside an IRA.
What happens when you die
Inheritance is where the two diverge sharply. A qualified annuity passes to heirs as pre-tax money: beneficiaries owe ordinary income tax on what they withdraw, and most non-spouse beneficiaries must empty the account by the end of the 10th year after the owner's death. If the owner had already started RMDs, they must also take a minimum each year in years 1 to 9. Some heirs (the owner's minor children, disabled or chronically ill heirs, and anyone no more than 10 years younger than the owner) can stretch withdrawals over their own life expectancy instead.
A non-qualified annuity gets no step-up in cost basis at death — unlike, say, appreciated stock — so heirs still owe ordinary income tax on the gain. But the principal you already paid tax on passes tax-free. Non-qualified contracts have their own clock, though: if the owner dies before payments begin, a non-spouse beneficiary generally must take the whole balance within five years or start life-expectancy payments within one year (IRC §72(s)). A surviving spouse can typically continue either contract as their own.
How to decide — and next steps
Work the question in order: first the money, then the job, then the cost.
- Identify the source. Is the money pre-tax (IRA/401k) or after-tax? That alone tells you whether it's a qualified or non-qualified annuity.
- Name the job. Do you want tax-deferred growth, guaranteed lifetime income, or RMD deferral? Match the job to the source using the matrix above.
- Price the alternative. If you're funding from an IRA "for taxes," stop — you already have deferral. Compare the all-in fees against a plain IRA or brokerage holding.
- Check the surrender terms. Confirm you won't need the cash during the surrender period before you commit.
Bottom line: qualified means pre-tax money — fully taxed on the way out, with RMDs. Non-qualified means after-tax money — only the gains are taxed, with no contribution cap and no RMDs. Inside an IRA, buy an annuity for what it guarantees (lifetime income, or a MYGA's fixed rate weighed against IRA CDs and Treasuries), never for tax deferral you already have.