The bucket strategy with annuities: a 3-bucket retirement plan
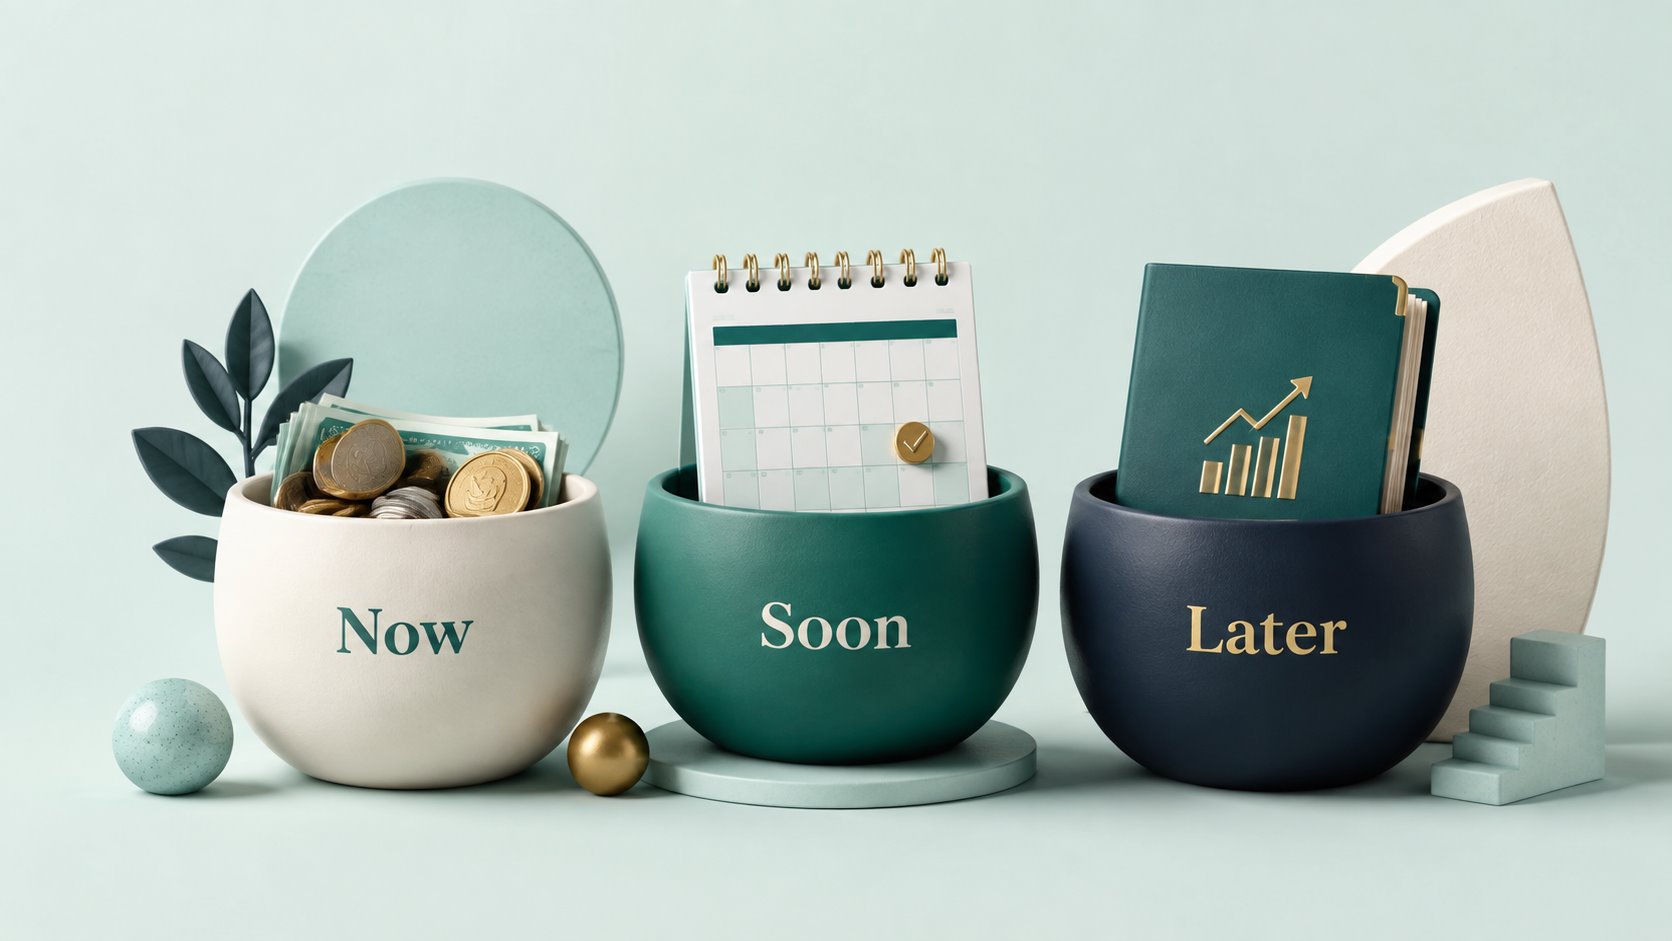
The bucket strategy organizes retirement assets into time-horizon buckets: cash for now, safe yield for soon, growth for later. Adding an annuity bucket dramatically reduces sequence-of-returns risk.
The bucket strategy organizes retirement money by when you'll spend it — cash for now, safe yield for soon, growth for later — and an annuity is a natural fit for the long-horizon bucket, turning "money for the far future" into "income I can't outlive." Done right, that guaranteed deep-future bucket is what lets you stay invested in growth through a downturn instead of panic-selling at the bottom. This guide covers how the buckets work, exactly where the annuity slots in, the numbers behind sizing it, who it's right for, and the mistakes that quietly undo the plan.
The classic three buckets
The idea is simple: don't hold all your retirement money in one undifferentiated pot. Divide it by time horizon so that the money you need next year is never exposed to the market, and the money you won't touch for a decade can stay invested for growth.
- Bucket 1 — now (0–2 yrs): cash, money-market funds, and short instruments. This is spending money, immune to market drops.
- Bucket 2 — soon (3–10 yrs): short and intermediate bonds and conservative holdings. Its job is to refill Bucket 1 as you spend it down.
- Bucket 3 — later (10+ yrs): growth equities — and/or a guaranteed-income annuity that covers the far future.
Money flows downhill: equities in Bucket 3 are harvested in good years to top up Bucket 2, and Bucket 2 feeds Bucket 1. The structure buys time, which is the only real defense against a bad market early in retirement.
Illustrative single-life payout by starting age — representative levels for A.M. Best A− and above carriers, not a survey or quote. Payout levels as of October 2026. A female buyer's check runs about 4.2% lower at 65 and 7.1% lower at 80, reflecting longer life expectancy. Actual quotes vary by carrier, state, sex and payout option.
Sequence-of-returns risk: the problem the buckets solve
Sequence-of-returns risk is the danger that a poor run of returns in the first years of retirement does outsized damage — because you're selling shares to live on while prices are down, locking in losses you never recover. Two retirees can earn the same average return over 30 years and end up in completely different places depending purely on the order of those returns.
Buckets blunt this by giving you two-plus years of spending that you never have to sell equities to fund, plus a bond layer to refill it. But the buckets alone have a weak point: in a long bear market, Bucket 1 drains, Bucket 2 thins, and the retiree faces the choice every plan dreads — sell growth assets at the worst possible time, or run short. That's where the annuity earns its place.
Where the annuity slots in
There are two distinct ways to use an annuity inside this framework, and they solve different problems.
- As longevity insurance in Bucket 3: a deferred income annuity (DIA) or a QLAC bought now to begin income at, say, 80 or 85 guarantees the deep-future bucket. Because that money can't run out, you can spend earlier buckets with confidence instead of stretching every dollar to age 100.
- As the income floor under Buckets 1–2: a SPIA (single-premium immediate annuity) that covers essential costs means a market downturn never threatens necessities, so your growth assets get the years they need to recover.
The behavioral payoff is the point. Knowing the far-future bucket is guaranteed makes it psychologically — and therefore financially — safe to stay invested through volatility. The failure most retirees actually suffer isn't a bad portfolio; it's selling growth assets in a panic. An annuity that puts a floor under essentials removes the trigger for that panic.
Annuities are insurance products regulated at the state level; you can verify how they work and how an insurer is overseen through the National Association of Insurance Commissioners and your state insurance department, and review investor-protection basics at FINRA.
The three buckets, with an annuity slotted in
| Bucket | Horizon | Holdings | Job |
|---|---|---|---|
| 1 — Now | 0–2 yrs | Cash / money market | Spending you never sell stocks to fund |
| 2 — Soon | 3–10 yrs | Short / intermediate bonds | Refills Bucket 1 in down markets |
| 3 — Later | 10+ yrs | Growth equities + DIA/QLAC | Long-term growth plus guaranteed deep-future income |
A worked example: sizing the annuity slice
Numbers make this concrete. Say you retire at 65 with a $1,000,000 portfolio and your essential annual spending is $60,000. Social Security covers $30,000 of that, leaving a $30,000 essential gap you'd rather not depend on the market to fill.
Suppose a single-life SPIA bought at 65 pays a man roughly 8.4% of premium per year for life (an illustrative figure — your actual quote depends on age, sex, rates, and features). To generate $30,000 a year, you'd commit about $30,000 ÷ 0.084 ≈ $357,000. That's more than a third of the portfolio gone to an annuity — a heavy commitment. It floors your essentials but leaves less room for growth and liquidity.
Now run the deferred version. A DIA/QLAC bought at 65 to start at 80 pays far more per premium dollar because of the 15-year deferral and mortality credits — illustratively, perhaps 25% of premium per year once it begins. To buy that same $30,000-a-year floor starting at 80, you might commit only about $30,000 ÷ 0.25 = $120,000 — roughly 12% of the portfolio. The remaining $880,000 covers ages 65–80 from Buckets 1–2 and stays invested for growth, and your essential income is covered for life by the annuity's guarantee (backed by the issuing insurer, not by any government agency).
Who it's right for — and who should skip it
This approach shines for some retirees and adds needless complexity for others.
- Good fit: you have enough assets to cover the early years yourself, you're worried about outliving your money, you tend to get nervous in downturns, and you want a guaranteed floor under essentials. Family longevity strengthens the case.
- Probably skip: Social Security and a pension already cover your essential spending (you're effectively annuitized), your assets are modest enough that liquidity matters more than longevity insurance, or your health and family history point to a short life expectancy.
Pros and cons at a glance
| Pros | Cons |
|---|---|
| Guaranteed lifetime income you can't outlive | Annuitized money is illiquid |
| Removes the panic-sell trigger in downturns | Exposed to the insurer's credit; state guaranty coverage has limits |
| Lets growth assets stay invested longer | Fixed payouts erode with inflation unless you add a COLA rider |
| A QLAC can defer RMDs on the annuitized amount | More moving parts than a two-fund portfolio |
The QLAC angle is worth a closer look: a qualified longevity annuity contract bought inside a traditional IRA or 401(k) lets you defer required minimum distributions on the amount used, within IRS dollar limits. The limit is indexed and set by the IRS ($210,000 for 2026) — confirm the figure for your year in the IRS's annual retirement-plan limits notice before you buy.
Mistakes that quietly undo the plan
- Over-annuitizing the long bucket. Annuitize essential deep-future income, not the whole of Bucket 3. Commit too much and you trade away the strategy's flexibility and any legacy.
- Ignoring inflation. A level payout that looks generous at 65 buys far less at 85. Consider a cost-of-living rider, or size the annuity to cover a fixed slice rather than your whole essential budget.
- Chasing the highest payout. The top quote may come from a weaker insurer. Weigh the rate against financial strength, and know your state guaranty association limit per insurer, per person — a capped backstop, not a substitute for that strength.
- Forgetting beneficiaries and liquidity. A pure life-only annuity stops at death. If leaving money to heirs matters, add a period-certain or cash-refund feature — and never annuitize money you might need for an emergency.
How to build it: next steps
- Map your essential vs. discretionary spending. Only essentials need a guaranteed floor.
- Net out guaranteed income. Subtract Social Security (estimate yours at ssa.gov) and any pension to find your true income gap.
- Decide SPIA now or DIA/QLAC later. Use a SPIA to floor essentials immediately, or a DIA/QLAC to insure the deep future for far less premium.
- Size the slice, then fund the buckets. Annuitize only the essential gap; fill Buckets 1 and 2 to bridge to the income start date; leave the rest in growth.
- Shop at least three highly rated insurers and re-confirm quotes the day you commit, since rates move.