How to retire on $2 million with annuities
At $2M, you have flexibility most retirees don't. The question shifts from 'will I have enough?' to 'how do I optimize income, taxes, and legacy?' Here's the annuity role at $2M.
At $2 million, the question shifts from "will I run out?" to "how do I make this efficient, resilient, and tax-smart?" The short answer: use a small, surgical annuity to guarantee your essential bills, then put the much larger remainder to work on growth, tax efficiency, and legacy. This guide shows how annuities fit a $2M plan, the real numbers, who should use one and who should skip it, and the mistakes that quietly drain wealth at this level.
Annuities as a precision tool, not the plan
With $2M, Social Security plus a modest annuity can usually floor all essential spending, freeing the large remainder to be invested aggressively enough to beat inflation and build legacy. The annuity here buys behavioral calm and sequence-risk protection, not survival.
That distinction matters. At smaller balances an annuity is often a lifeline; at $2M it is a tool you choose deliberately because guaranteed income lets you stay invested through downturns without panic-selling. You are buying permission to take more equity risk with the rest of the portfolio, which is where most of your long-term growth and legacy will come from.
Illustrative single-life payout by starting age — representative levels for A.M. Best A− and above carriers, not a survey or quote. Payout levels as of October 2026. A female buyer's check runs about 4.2% lower at 65 and 7.1% lower at 80, reflecting longer life expectancy. Actual quotes vary by carrier, state, sex and payout option.
How the income floor actually works
The mechanics are simple. Add up your non-negotiable annual spending — housing, food, insurance, utilities, taxes, basic transportation. Subtract the guaranteed income you already have, primarily Social Security. Whatever gap remains is the only piece you need an annuity to cover.
Delaying Social Security is usually the cheapest "annuity" you can buy. Each year you wait from full retirement age to 70 raises your benefit by roughly 8%, and it is inflation-adjusted for life — see the Social Security Administration for your specific numbers. Only after maximizing that base do you size a commercial annuity to fill the rest.
A single premium immediate annuity (SPIA) starts paying within a year. A deferred income annuity (DIA) starts later for a higher payout. A QLAC is a DIA held inside an IRA that is structured to defer required minimum distributions. You can review the basics of how these contracts are regulated and sold at FINRA.
A worked $2M example
Say your essentials run $80,000/yr and delayed Social Security covers $45,000/yr. That leaves a $35,000/yr gap to floor.
At an illustrative 7% SPIA payout rate for a couple in their late 60s, $35,000 of annual income costs about $35,000 ÷ 0.07 ≈ $500,000 — roughly 25% of the $2M. Keep about $120,000 (around 1.5 years of spending) in cash as a buffer, and you still have $1.38M to invest across taxable, tax-deferred, and Roth accounts. A payout rate is not an interest rate: most of each early check is your own principal coming back to you, so the percentage is not comparable to a bond or CD yield.
Now compare that to drawing the same $35,000 from the portfolio at a 4% rate: $35,000 ÷ 0.04 = $875,000 of assets "reserved" to safely produce it. The annuity floors the same income for $500,000 because it also returns principal and pools longevity risk — so it can free up capital while removing the bills from market risk. It isn't quite like-for-like, though: 4%-rule withdrawals rise with inflation and often leave a balance for heirs, while a level SPIA pays the same amount every year. An inflation-adjusted SPIA would cost noticeably more, though typically still less than $875,000. The tradeoff is liquidity: that $500,000 is no longer available for emergencies or heirs.
SPIA vs. portfolio withdrawal: the trade
| Factor | $500K SPIA (floors $35K/yr) | $875K kept invested (4% rule) |
|---|---|---|
| Income certainty | Guaranteed for life | Depends on markets |
| Liquidity | Largely gone after purchase | Fully accessible |
| Inflation protection | None unless you add a rider | Equities can outpace inflation |
| Legacy value | Low (unless period-certain) | Remaining balance passes to heirs |
| Sequence-risk shield | Strong — bills untouched by crashes | Weak in an early downturn |
| Capital "reserved" | ~$500,000 | ~$875,000 |
A clean $2M structure
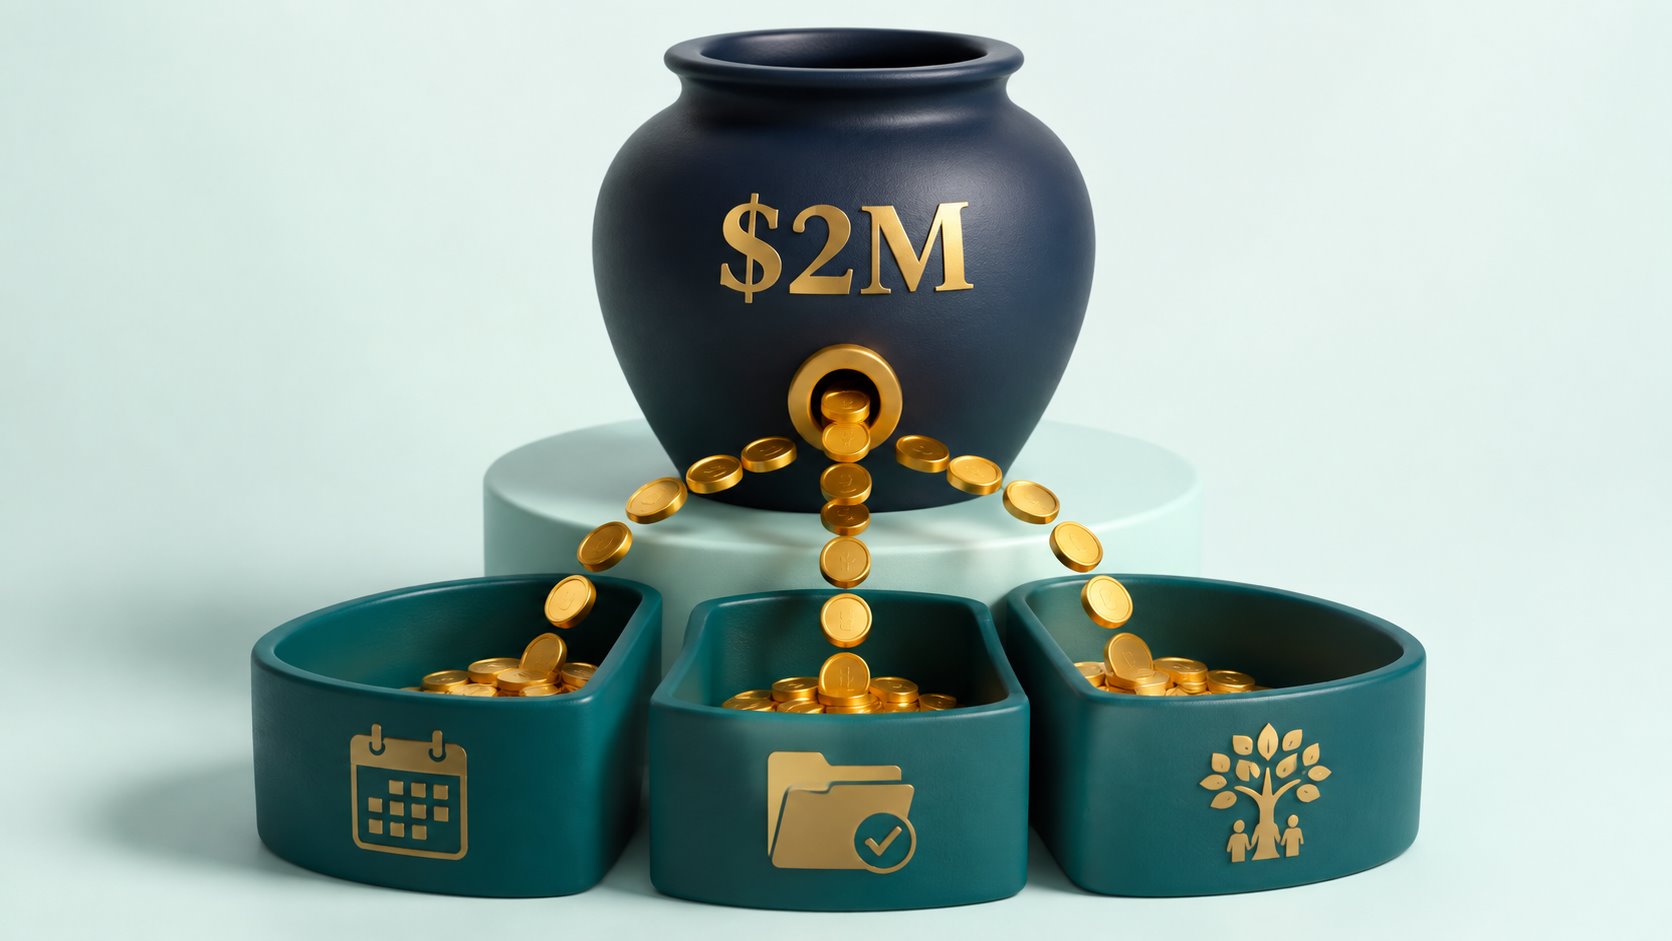
- Floor essentials with delayed Social Security + a right-sized SPIA/DIA (often only 10–25% of assets).
- Cash buffer: 1–2 years of spending so you never sell investments into a downturn.
- Tax management: coordinate withdrawals across taxable, tax-deferred, and Roth to control brackets and the taxation of Social Security.
- Growth + legacy: invest the bulk for total return; consider a QLAC to defer RMDs and trim taxable income in your 70s.
The IRS RMD and QLAC rules drive much of the tax-efficiency opportunity at this level, which is why the annuity decision and the tax decision should be made together, not separately.
Who it's for — and who should skip it
An annuity earns its place at $2M when at least one of these is true for you:
- You would panic-sell in a downturn without guaranteed income, and that behavior risk is real, not theoretical.
- Your essentials are not fully covered by Social Security and any pension.
- You expect a long life (good health, family history) and value longevity pooling.
- You want one less decision to manage as you age.
You can probably skip it — or buy only a token amount — when Social Security and a pension already cover essentials, when leaving a large inheritance is a top priority, or when you are confident you will stay invested through volatility. Liquidity has real value at $2M; do not give it up for income you do not need.
Pros and cons at $2M
Pros: guaranteed lifetime income, protection from a bad market early in retirement, longevity-risk pooling, and the behavioral freedom to keep the rest of the portfolio in growth assets.
Cons: reduced liquidity, limited or no legacy value on a basic contract, inflation erosion on level payouts, insurer credit risk, and an opportunity cost if markets do well. Annuities are obligations of the issuing insurer, not the government, so credit quality and your state guaranty association limits matter — confirm both before you commit, and review how products are marketed at the SEC and your state insurance department.
Where bigger portfolios actually leak value
Two mistakes dominate at this level. The first is over-annuitizing — buying more guaranteed income than your essentials require, when liquidity and tax control are usually worth more. The second is ignoring RMD and tax drag: once RMDs begin in your 70s, forced distributions can push you into higher brackets and tax more of your Social Security.
A QLAC to defer a slice of RMDs, plus measured Roth conversions in your lower-income early-retirement years, often add more lifetime value than another annuity dollar. See tax-efficient annuity income for how to sequence these moves.
How to do it — next steps
- Quantify essentials vs. wants. Only essentials need a guaranteed floor.
- Maximize Social Security first — usually the best inflation-adjusted income you can buy.
- Size the gap, then the annuity using the worked-example math above.
- Shop quotes from several highly rated insurers; payouts vary, and rates move with interest rates.
- Coordinate taxes — model RMDs, Roth conversions, and a possible QLAC together.
- Invest the remainder for total return and legacy, with a 1–2 year cash buffer.